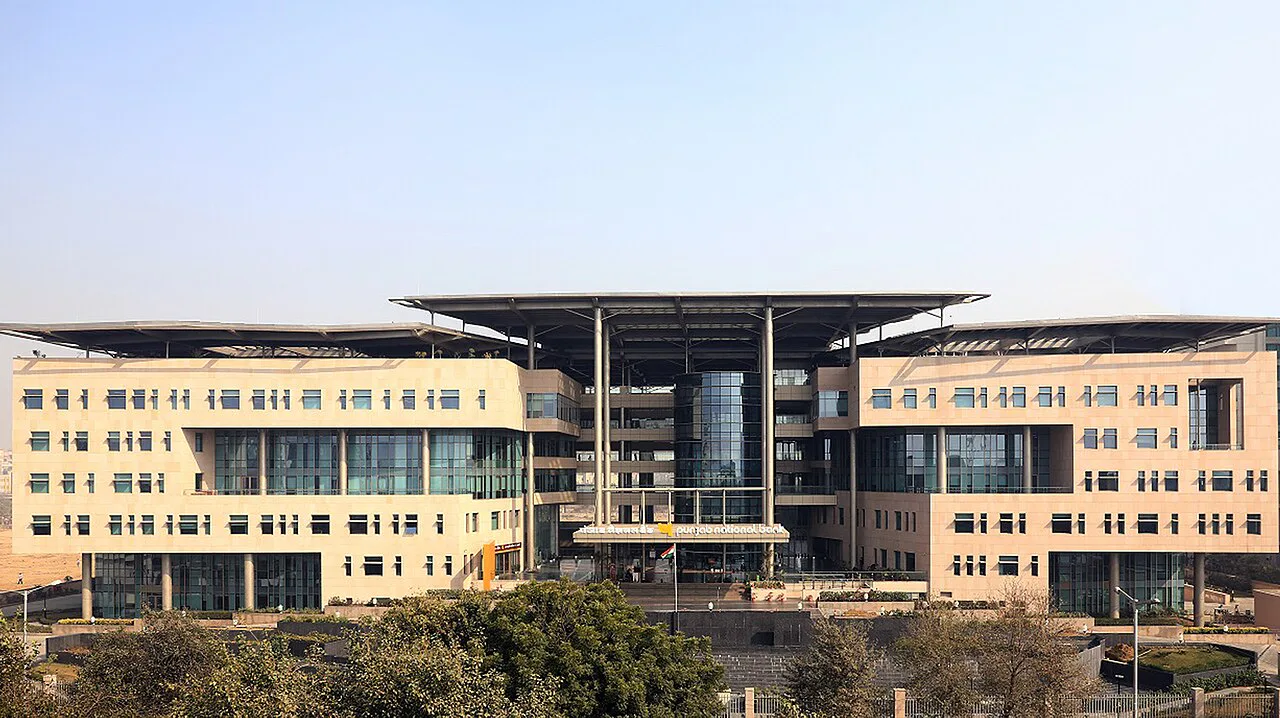
GYFTR Limited signed a three-year agreement with Punjab National Bank on August 14, 2026, to operate a dedicated website where credit cardholders can buy discounted gift vouchers and coupons. The company disclosed the project in a stock exchange filing. [S01]
The contract covers the operating platform
| Contract element | Disclosed scope [S01] |
|---|---|
| Term | Three years |
| Technology | Development, deployment and management of a dedicated microsite |
| Payments | Payment gateway and related technical support |
| Contract value | The disclosure marks the consideration field “Not Applicable” |
The filing gives no launch date, merchant list or discount schedule. Its consideration entry does not mean the service is free, and no fee split is disclosed. It identifies the deal as ordinary-course business, not a related-party transaction. [S01]
Why the identity of the supplier matters
The contracting company is the listed GYFTR Limited, formerly LKP Finance Limited. Its January 7 disclosure records a licence for the GyFTR trademark from Vouchagram India Private Limited, a group company, with annual licence fees. The listed licensee and the brand licensor are distinct legal businesses. [S02]
The licence followed a change to the company's business objects allowing new and allied activities. In that context, the bank agreement supplies a concrete example of the listed company putting a licensed gifting identity to commercial use. It does not establish ownership of every business or customer relationship associated with the wider brand. [S02]
The broader GyFTR proposition helps explain the service being sold. Its corporate brochure describes white-label programmes for banks, employers and retail brands, with technology connecting clients to voucher distribution and redemption. The business combines software with access to branded rewards. This is useful background to the market; it is not evidence that the bank contract includes the full catalogue or every feature described in that brochure. [S04]
What the bank and the platform stand to gain
Punjab National Bank is a major Indian public-sector bank whose operations began in 1895. Its June 2026 profile records 10,359 domestic branches and 27 million activated users of its PNB One digital service. Those figures show the scale of the banking franchise, not the number of credit cardholders eligible for the new voucher site. [S03]
For the bank, discounted vouchers can give cardholders another reason to return to a service associated with their card. A purchase benefit can reinforce the relationship between everyday shopping and the banking product. The commercial attraction is repeat engagement and a potentially more useful card proposition. Neither the branch count nor digital-user total establishes demand for this particular offer. [S03]
For GYFTR, the agreement creates a distribution route through an existing cardholder relationship, rather than requiring every shopper to be acquired individually. For participating retail brands, voucher distribution can bring purchase intent from a banking audience. A specialist platform can connect those two sides without the bank building the entire merchant and voucher operation itself. This is an interpretation of the operating model, not a reported cost saving. [S04]
Discount funding and per-purchase economics remain undisclosed. A signed agreement establishes a project; a working offer and purchase volumes will determine its commercial weight. [S01]
In this article
Suzie Elis
Suzie Elis covers gift card products, digital gifting and distribution for Gift Card News.