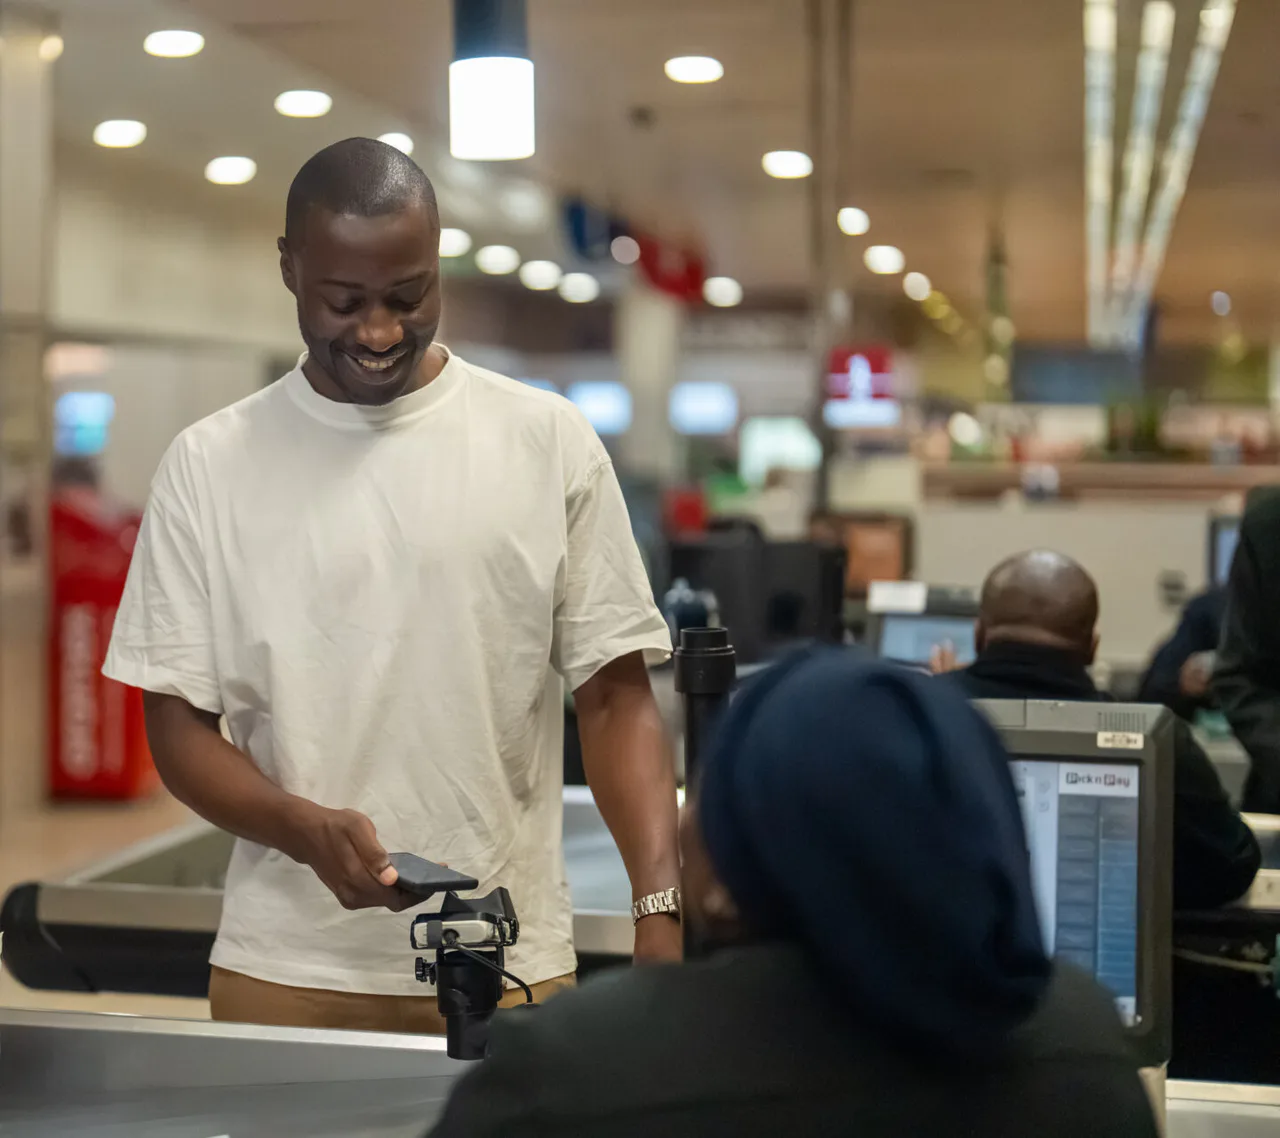
Yoyo's case for card-linked loyalty is also a case for placing rewards inside the merchant's payment relationship. The company describes a system in which a qualifying card payment identifies the loyalty account and triggers the reward, removing the separate scan or coupon that customers can forget at checkout. [S01]
The commercial attraction is not simply a shorter transaction. A loyalty provider connected to the point of sale can participate in repeat purchases throughout the life of the merchant relationship, rather than supplying rewards only when a marketing team orders a campaign.
A route through the payment provider
The proposition has a visible distribution channel. Peach Payments lists Yoyo rewards within its Digit Pro point-of-sale offer, with customer enrolment by mobile number, earning through card or digital-wallet payments, and redemption on the terminal. Its page also identifies gift cards for enterprise merchants and partial redemption. [S02]
Peach Payments supplies the payment acceptance service; Yoyo supplies the rewards functionality attached to it. Combining those roles can give the payment provider another reason for merchants to use its terminals and give Yoyo access to businesses already buying payment services.
Those are commercial opportunities inherent in the arrangement. The public product page does not disclose the parties' revenue split or demonstrate how many merchants chose the payment provider because of loyalty.
The transaction becomes a customer signal
Yoyo's explanation describes the point of sale sending a tokenised identifier with transaction details so the loyalty system can apply the relevant earning rule. It distinguishes an ongoing programme from a temporary card-linked promotion. [S01]
That distinction changes what the retailer buys. A one-off offer funds a particular incentive. An ongoing system can connect a succession of purchases, making the supplier part of how the merchant records and rewards the customer relationship.
The potential gain is more consistent recognition of qualifying purchases. The limitation is that a more complete record still does not prove that the reward caused the spending. Customers who join a programme may already be the retailer's most frequent buyers.
For gift card operators, the connection matters where stored-value rewards form part of that programme. It does not turn every payment card into a gift card or make a merchant's prepaid balance spendable everywhere.
Convenience has boundaries
Yoyo's material acknowledges that integration and certification depend on the point-of-sale environment. It also notes that cash purchases need another way to identify an earning event. [S01] A retailer therefore still has to consider customers whose transactions do not produce the same payment-linked signal.
The business decision is a trade-off between less visible effort at checkout and more reliance on the connection behind it. Faster recognition can make a reward easier to earn and use; the resulting cost and additional purchasing need to be assessed separately.
The strongest interpretation of Yoyo's positioning is that loyalty belongs close to the event being rewarded. Whether that creates profitable retention depends on the merchant's economics. What the integration clearly offers the two suppliers is a way to sell a more connected service around transactions they want to keep handling.
In this article

Oliver Reed
Oliver Reed covers industry acquisitions, investment and market research for Gift Card News.