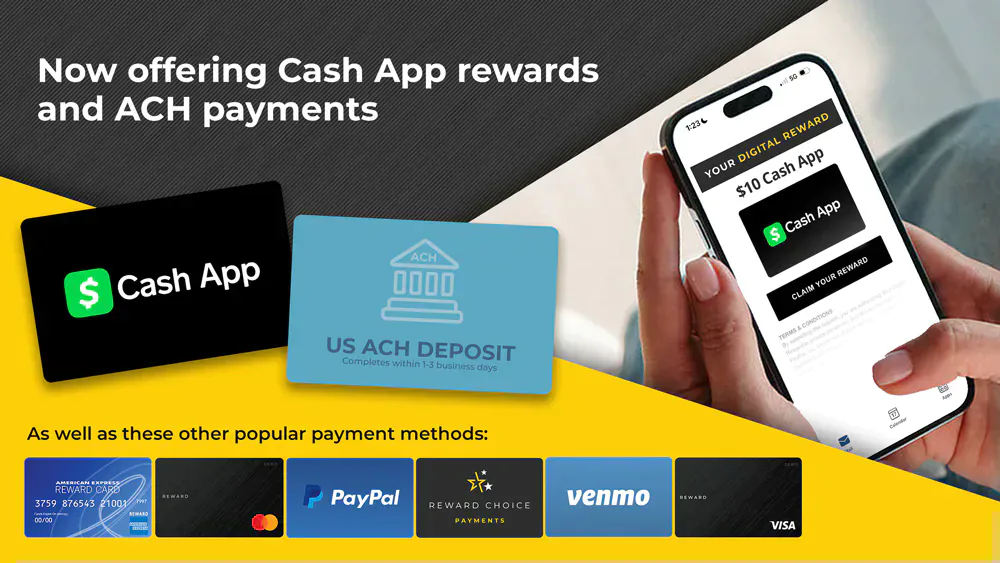
NeoCurrency added Cash App and ACH bank deposits to its US reward options on April 14, 2026, extending a gift card distributor's reach into payouts that recipients can use beyond a particular retailer. The move puts more redemption decisions inside the same corporate rewards relationship. [S01]
Customers can include the new methods in Reward Choice, which lets a recipient allocate an available balance across more than one option. NeoCurrency said the additions responded to demand for flexible, cash-like payments. It did not publish adoption figures or a breakdown of the revenue attached to each method. [S01]
A rewards intermediary widens the menu
NeoCurrency supplies incentives for promotions, research participation, employee recognition and loyalty programmes. Geoff Miller, its founder and chief executive, came from advertising and online rewards work. That background helps explain why the company sells delivery infrastructure to programme owners rather than presenting itself as a consumer bank. [S03]
The company's commercial relationship begins with the organisation funding a reward. A recipient selecting a bank transfer instead of a retailer's gift card changes where the money ends up, but need not change which provider manages the reward. That is the strategic value of adding payment methods to an existing distribution interface.
For a research platform, the practical difference is between arranging separate suppliers for respondents who want cards and those who want cash, or offering both through one programme. This is a potential procurement advantage, not a claim that all methods have identical costs, verification requirements or arrival times.
The price model matters more than the catalogue size
NeoCurrency's public pricing page describes a prefunded service without a platform subscription, setup charge or monthly retainer. It offers discounted rewards and supplies price lists to dashboard and API customers. The company separately discloses a 0.9% charge when customers move funds across currencies using its self-service conversion tool. These are current general terms, not a published Cash App or ACH rate card. [S02]
That model gives context to the expansion. The provider has an interest in retaining the organisation's recurring reward orders, even when the recipient's preferred form of value changes. But a broader menu does not itself prove higher margins. The prices paid to suppliers, transaction expenses and negotiated customer terms would determine the economics of an individual payout.
The distinction also matters for gift card issuers. A cash option may compete with a branded reward for the same funded balance. Equally, a programme able to accommodate different preferences may win a customer that would not otherwise use its catalogue. The announcement supplies no evidence showing which effect dominates.
Choice does not remove operational conditions
NeoCurrency's launch statement describes verification steps for the new methods. ACH means a deposit to a bank account; Cash App is a mobile payment service. Neither should be confused with a universally available, unrestricted gift card, and the announcement does not establish one guaranteed settlement time for every recipient. [S01]
The commercial test is therefore specific: whether the new methods attract or retain programme spending, reduce unresolved redemptions and leave an acceptable contribution after delivery costs. A larger list of payout logos is an input to that proposition, not the result.
In this article
Emma Carter
Emma Carter covers retail, e-commerce and the gift card shopping experience for Gift Card News.