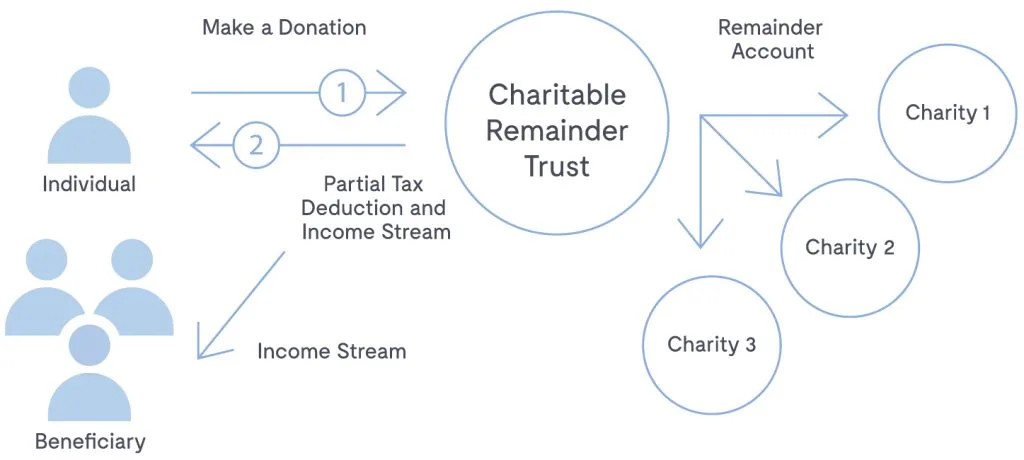
Fieldpoint Private has published an overview of charitable trust structures for donors considering planned gifts, using the approach of Giving Tuesday to discuss arrangements that combine charitable giving with an income interest. The November 20, 2025 paper focuses on charitable remainder unitrusts and two variations, NIMCRUTs and FLIP-CRUTs.
The paper begins with direct gifts to charities, foundations and donor-advised funds before turning to split-interest trusts. In the charitable remainder structure it describes, a non-charitable beneficiary receives distributions during the trust’s term and the remaining assets pass to charity at its end.
Fieldpoint explains that a standard charitable remainder unitrust bases its annual distribution on a percentage of the trust’s asset value. Its discussion then contrasts that arrangement with a net-income-with-makeup charitable remainder unitrust, or NIMCRUT, where the available trust income affects the amount distributed.
The paper uses numerical illustrations to explain how a NIMCRUT can record distribution shortfalls and make up amounts in later years when sufficient income is available. It also presents a hypothetical business owner contributing interests in limited liability companies, using that example to discuss the relationship between underlying asset income and trust distributions.
A further section considers the FLIP-CRUT, which the paper describes as changing from a net-income arrangement to a standard unitrust after a specified event or date. Fieldpoint notes that this change is permanent and that remaining makeup amounts are forfeited when the conversion takes effect.
The discussion frames these structures as matters for individual planning and identifies tax and valuation constraints, including adjusted-gross-income limits, asset-basis considerations and trust accounting rules. The publication identifies the service provider as Fieldpoint Private Trust, LLC, a public trust company chartered in South Dakota.
Sources and documents
Collapse
- Giving Tuesday (Doing Well by Doing Good!) — fieldpointprivate.com
In this article
Emma Carter
Emma Carter covers retail, e-commerce and the gift card shopping experience for Gift Card News.