An email contains a gift card. The balance checker says $2.37. There is nothing you want for that amount, and buying something more expensive means adding your own money. Before treating the remainder as a discount on another purchase, there is another question worth asking: can the issuer give it back?
In parts of the United States, the law provides a route to recover a small remaining balance. Elsewhere, the answer may depend on the merchant's policy. Even where a right exists, the headline dollar amount is only the beginning: some states require a previous purchase, some exclude particular kinds of cards, and others distinguish a standalone digital code from money already loaded into an online account.
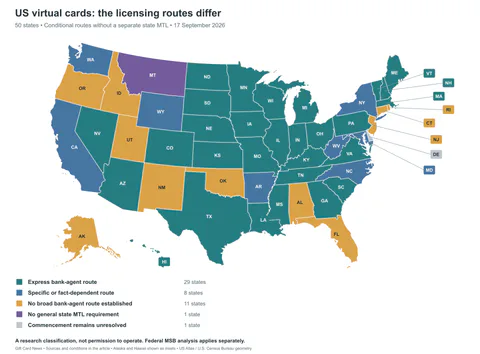
This investigation reviews all 50 states, with the District of Columbia separately. It identifies 14 states with cash-redemption provisions, including Rhode Island's qualified wording, consistent with the National Conference of State Legislatures' May 2026 comparison. The map describes those provisions and their limits; it does not establish that every card held by every resident qualifies. [S01]
The focus is digital merchant gift cards. Bank-issued Visa or Mastercard gift cards, promotional rewards, merchandise-return credits and account balances require separate attention. The state entries link to the legal material reviewed and identify the source basis for each conclusion.
The map: where a small balance can become cash
Read the symbols literally. “< $5” means less than $5; a balance of exactly $5 is outside that threshold. “≤ $5” includes exactly $5. Massachusetts has a percentage-based rule for nonreloadable cards and a separate dollar rule for reloadable cards. Rhode Island's statute links reissuance with cash in wording that warrants care. Grey means that no general small-balance cash-out requirement was identified in the reviewed materials—not that redemption is prohibited or that other consumer protections disappear.
T01. The 14 states with cash-redemption provisions
Show data tableHide data table
| State | Monetary test | Key condition—not the complete eligibility rule | Legal source |
|---|---|---|---|
| < $15 | Operative April 1, 2026; covered products only. | Statute [S02] | |
| ≤ $5 | Holder requests cash; exactly $5 is included. | Statute [S03] | |
| < $5 | After a purchase; retailer and product exclusions apply. | Statute [S04] | |
| < $5 | Qualifying retail instrument; strictly below $5. | Statute [S05] | |
| < $5 | In-person redemption; original value above $5; account-balance exclusion. | Statute [S06] | |
| ≥90% used / reloadable ≤ $5 | Nonreloadable: at least 90% redeemed. Reloadable: partly used, remaining ≤ $5. | Statute [S07] | |
| < $5 | Original value above $5; remaining value below $5. | Statute [S08] | |
| < $5 | After redemption; initial ≤ $5 nonreloadable cards excluded. | Statute [S09] | |
| < $5 | Open-loop and promotional cards excluded. | Statute [S10] | |
| < $5 | At least one purchase; cards redeemed to online accounts excluded. | Statute [S11] | |
| < $1 — qualified wording | Reissue-or-cash wording; consumer election not expressly stated. | Statute [S12] | |
| < $2.50 | After in-person purchase; initial ≤ $5 nonreloadable cards excluded. | Statute [S13] | |
| < $1 | On demand; a separate expired-value provision also exists. | Statute [S14] | |
| < $5 | After a purchase leaves less than $5. | Statute [S15] |
The coloured states are a starting point for checking eligibility. Product exclusions, purchase history and the connection between the transaction and the state can change the answer. The detailed entries below explain those conditions.
Why the money matters—and what the data actually measure
Bankrate's 2024 survey found that 43% of U.S. adults held unused gift cards, vouchers or store credits. Among holders, the mean was $244; the median was $100. Its generational breakdown put millennials at $332, Gen X at $255, baby boomers at $227 and Gen Z at $142. These figures describe a mixture of products and delivery formats, not exclusively virtual merchant cards. [S16]
F02. Unused value differed by generation
Mean value among holders of unused gift cards, vouchers or store credits, United States, 2024.
USD
Tap or hover for details. All values are also available in the data table.
Holder-only averages from an online YouGov survey for Bankrate, August 19–21, 2024: 2,373 U.S. adults, including 1,010 holders of unused value. Quotas and weighting were used. These are combined balances, not individual card amounts, statutory cash-out entitlements or permanent losses. Subgroup sample sizes are not reported. Statista presents the same Bankrate/YouGov study; it is not an independent survey.
Show data tableHide data table
| Category | Mean unused value |
|---|---|
| Millennials | 332 USD |
| Gen X | 255 USD |
| Baby boomers | 227 USD |
| Gen Z | 142 USD |
Bankrate commissioned an online YouGov survey of 2,373 U.S. adults, including 1,010 holders of unused value, on August 19–21, 2024. Quotas and weighting were used. Group means are not individual card balances or amounts eligible for cash redemption; subgroup sample sizes are not supplied in the report.
The distinction matters. A person with several large cards may have substantial unused value and no small-balance entitlement on any one card. Someone with a few cents on one qualifying card may have a valid claim. An unused balance is also not necessarily a permanent loss: the owner may still intend to spend it.
A small balance is one obstacle among several
In Accenture’s 2024 findings presented by Statista, 25% of consumers with an unused balance said the amount was too small to use. Limited merchant choice and forgetting the card each drew 34%. This identifies a spending obstacle, not a legally redeemable balance. [S143]
F03. One in four cited an amount too small to use
United States, 2024. Accenture online survey of 483 consumers with unused gift-card balances.
%
Tap or hover for details. All values are also available in the data table.
Source
Multiple responses allowed; categories overlap. Labels paraphrased. Statista does not specify exact fieldwork dates. These responses do not measure cash-out eligibility, refused payouts or awareness of state law.
Show data tableHide data table
| Category | Respondents |
|---|---|
| Limited merchant choice | 34% |
| Forgotten card | 34% |
| No suitable item | 28% |
| No time to use it | 28% |
| Unappealing choices | 28% |
| Amount too small to use | 25% |
| Restricted redemption channel | 23% |
| Technical redemption problems | 23% |
| Card expired | 22% |
| Insufficient flexibility | 20% |
| Sign-up required | 18% |
| Card lost | 17% |
Unused today does not mean abandoned forever
CivicScience distinguished respondents who planned to spend their unused cards soon: 21% selected that answer in both chart years. The share reporting no unused cards was 35% in 2024 and 39% in 2025. The survey filters out people who do not typically buy or receive gift cards. [S144] [S146]
F04. Ownership and spending plans tell different stories
U.S. adults who typically buy or receive gift cards. CivicScience chart labels, 2024 and 2025.
%
Tap or hover for details. Select a series above to show or hide it.
Weighted to U.S. Census demographics. The original chart reports 1,865 responses across January 25, 2024–January 6, 2025; separate yearly sample sizes are not stated. This filtered population differs from Bankrate’s all-adult survey, so the prevalence figures are not directly comparable.
Show data tableHide data table
| Category | 2024 | 2025 |
|---|---|---|
| Many unused cards | 12% | 11% |
| A few unused cards | 32% | 29% |
| Unused, with plans to spend soon | 21% | 21% |
| No unused cards | 35% | 39% |
Gift-card purchasing remains substantial. For the 2025 holiday season, the National Retail Federation and Prosper Insights & Analytics reported $29.1 billion in expected gift-card spending, compared with $28.6 billion for 2024. Their survey covered 8,000 adult consumers from October 31 to November 6, 2025. These were holiday spending plans—not observed full-year market sales. [S17]
F05. Gift-card purchase plans extended beyond merchant cards
Selected gift-card types in the National Retail Federation’s 2025 holiday survey.
%
Tap or hover for details. All values are also available in the data table.
Source
Reported purchase intentions, not observed transactions or shares of gift-card sales. NRF and Prosper surveyed 8,000 adult consumers from October 31 to November 6, 2025. Selected categories are not exhaustive and do not form a 100% partition. The release does not provide the question’s complete subgroup base; bank-issued products have different legal coverage.
Show data tableHide data table
| Category | Reported purchase plans |
|---|---|
| Restaurants | 27% |
| Bank-issued cards | 25% |
| Department stores | 25% |
| Coffee shops | 20% |
NRF's reported purchase plans include restaurants, bank-issued cards, department stores and coffee shops. These percentages are not a division of total sales and do not sum to 100%; the release does not provide complete subgroup denominator detail.
None of these surveys establishes how much money Americans could legally cash out under current state thresholds, how often issuers refuse valid requests or what proportion of consumers successfully recover a balance. This guide therefore does not turn unused-card estimates into a national “cash waiting to be claimed” figure.
There is no single federal cash-out threshold
Federal Regulation E protects covered gift cards against certain expiration practices and fees. It covers qualifying emailed codes as well as conventional cards, but it does not create an unrestricted right to exchange a small balance for cash. Covered funds generally cannot expire before the later of five years after issue or last load, as applicable, or the card's stated expiration date. When the card expires before its funds, the issuer may provide a replacement or otherwise return the balance under the rule; that is not a general consumer election for cash. Qualifying promotional and reward products can be excluded subject to the rule's conditions. [S18]
Federal law preserves more protective state rules within their scope. It does not make a state's rules apply to transactions they otherwise would not cover. [S19]
That is why a consumer should resist two shortcuts: assuming the same dollar threshold applies nationwide, or assuming the issuer's home state is the only relevant jurisdiction. A digital purchase may connect the buyer, seller, issuer and redemption transaction to different places. The appropriate law can require a fact-specific assessment. A home address alone is not a universal eligibility test.
What changes at $3, $2 and $1?
The law operates through defined boundaries, not a gradual judgment about whether a balance feels too small to use. The following examples assume a covered product and an applicable state law; other conditions still matter.
T02. Why one cent can change the answer
Show data tableHide data table
| Remaining balance | What the threshold comparison tells you |
|---|---|
| $14.99 | Below California's current $15 threshold. This is not a nationwide right. |
| $5.00 | Included by Colorado's “$5 or less” rule. Excluded by the states using strictly “less than $5.” Massachusetts needs its own analysis. |
| $4.99 | Below the common $5 boundary, but requirements such as a previous purchase or original face value still apply. |
| $2.99 | Below $5; still above Texas's $2.50 boundary. |
| $2.49 | Below Texas's monetary boundary, subject to its in-person purchase condition and exclusions. |
| $1.00 | Not below the $1 thresholds appearing in Vermont and Rhode Island. |
| $0.99 | Below $1; Vermont's right and Rhode Island's differently worded provision still require separate treatment. |
Illustrations calculated from the statutes linked in the threshold table and state entries. They are threshold comparisons, not individualized eligibility decisions.
Massachusetts is especially easy to misread. For a nonreloadable certificate, redeeming at least 90% of the face value can trigger the cash election. On a $200 certificate, a $20 remainder after $180 of redemption can therefore meet the percentage condition. A partially used reloadable certificate follows a separate balance rule of $5 or less. Calling Massachusetts simply a “$5 state” misses the first route. [S07]
Before making another purchase to reach a threshold, compare its cost and any extra out-of-pocket spending with the amount you could recover. A small purchase paid from the card may sometimes leave a qualifying remainder; spending additional money to do so can also outweigh the benefit. Check the product and procedural conditions before assuming the transaction will create a cash-out right.
A digital gift card is not always the same legal product as an account balance
“Virtual” describes delivery and access. It does not settle the legal classification. An emailed merchant code, a reward distributed by an employer, a store-credit balance from a return and a bank-issued network card can all appear on a phone while operating under different terms and statutory definitions.
Two state rules make that distinction particularly concrete. Oregon's cash-out subsection excludes a card already redeemed to an online account; that wording should not be expanded into a claim that every electronic gift card is excluded. Maine's current definition distinguishes qualifying bearer gift obligations from account credits or balances, including balances funded with those obligations. In both places, the way value is held can matter alongside the amount. [S11]; [S20]
For a digital holder, this creates a practical question before transferring a code into an app or account: what happens to the original gift obligation, and which redemption rules will apply afterward? The answer comes from the relevant law and issuer terms, not merely the appearance of a “gift balance” label.
Visa and Mastercard: acceptance does not guarantee cash access
A payment-network logo tells you something about where a product can be spent. It does not by itself establish ATM access, purchase cash back or eligibility under merchant-card cash-out statutes. For example, Vanilla's own Visa gift-card FAQ says its product cannot be used for ATM withdrawals or cash back. That is a verified product example, not a rule covering every card bearing a Visa logo. [S21]
The state entries flag relevant exclusions for bank-issued or multi-merchant products. Do not apply a retailer's small-balance rule to a network gift card simply because the balance is low. Conversely, do not treat an issuer's ordinary “no cash access” feature as a complete analysis of every statutory refund or dispute right.
How to request the money
Start with the issuer or merchant responsible for the value. The company that delivered the email may be a distributor rather than the party that handles redemptions. Use the official website or the contact details attached to the gift card.
-
Identify the product. Is it an ordinary purchased merchant gift card, a bank-issued gift card, a promotional reward provided without charge, a return credit or an account balance?
-
Check the balance. Save the date, amount and a reference to the card. Keep the original purchase or gift receipt and relevant transaction history if available; a receipt is not a universal statutory requirement.
-
Check the applicable state entry. Read the comparator, original-value conditions, use-first requirements, exclusions and any in-person requirement.
-
Ask for the remaining balance under the applicable rule. Distinguish this request from returning a purchase or cancelling the original gift-card sale.
-
Ask how payment will be delivered. Do not assume the law requires an immediate bank transfer or that every issuer has an online redemption form. Request the issuer's approved process and timing.
-
Keep a written record of a refusal. Ask whether the reason concerns the product, the amount, the transaction's location or a procedural condition. An unexplained “gift cards are nonrefundable” answer does not resolve each of those questions.
A request you can adapt
I hold a [merchant/product] gift card with a remaining balance of $[amount]. I am requesting redemption of the remaining balance under [state and statutory section]. The relevant purchase occurred on [date/location], and [state any applicable use-first or original-value condition]. Please confirm the redemption procedure, or explain which eligibility condition you believe is not met.
Do not publish the full card number or PIN in a complaint narrative visible to others. Supply necessary details only through the issuer's or agency's secure channel. A legitimate small-balance request does not require paying a stranger with another gift card.
T03. Official issuer routes for digital-card holders
These links distinguish a verified payout form from a general support channel. A support link is a place to request the applicable procedure, not proof that every balance qualifies or will be paid remotely.
Show data tableHide data table
| Issuer / product | Verified application channel | What the primary source actually establishes |
|---|---|---|
| Apple Gift Card / redeemed Apple Account balance | Follow Apple's balance and cash-refund instructions [S22], then contact Apple Support [S23]. Include the primary email used to sign into the Apple Account. | The article, published 16 September 2026, expressly directs customers seeking a legally required refund of a redeemed gift balance to Support. No universal cash-out promise or completion time. Apple's separate instruction about clearing an unspendably small account balance before changing account settings is not itself a cash-refund promise. |
| Chipotle gift cards | Gift Card Cashback request form [S24]. | The page offers remaining-balance payout for cards below $10, or below $15 in California, through bank transfer or check. The form requests contact and mailing information; its mailing address instruction excludes PO boxes. This is a retailer's published program, not a statement that every state requires a $10 threshold. Its approximately ten-business-day estimate concerns hearing back from Customer Care, not guaranteed payment receipt. The page addresses gift cards generally and does not state a digital-only exclusion. |
| Google Play gift card / paid Play balance | Read Google Play gift-card refund policy [S25], then use its Contact us support entry point [S26], which leads to account sign-in. | US cash refunds are unavailable except when state or federal law requires them. Paid balances and promotional balances must be distinguished: the page says promotional balance is nonrefundable and nontransferable. This is an official support route, not a verified automatic residual-balance payout form. Problems with a third-party specialty gift card may need the issuing brand. |
| Starbucks Card, including eGift | Contact Starbucks at 1-800-782-7282, the official support number in the Starbucks Card terms [S27]. Ask for the procedure for a legally required remaining-balance redemption. | Terms treat eGift as a Starbucks Card and preserve cash refunds where required by law. They also prohibit transfers between cards solely to obtain cash back. A return of a wholly unused eGift is a separate topic. The terms do not specify counter service, a payout method or a processing time for residual-balance redemption. |
| Darden restaurant eGift cards | Contact guest relations at 800-331-2729, listed in the gift-card terms [S28]. | The terms expressly preserve legally required cash redemption, refer to state de minimis rules, and apply the same terms to eGift cards. Covered brands include Olive Garden, LongHorn Steakhouse, Yard House, Ruth's Chris and others. This is a general support route; the cited terms do not specify a dedicated cash-out form or processing time. The separate gift-card-services email in the terms is a formal dispute-notice channel, not an expressly designated first-line cash-out inbox. |
| Use the dedicated Target Gift Card contact page [S29]. For the amount, use Target's balance checker [S30]. | The dedicated channel and balance checker are verified. Target's Gift Card help page [S31] explains access to emailed/texted cards and retrieving access numbers through the Target account. Use this channel to request the applicable cash-redemption procedure. The cited pages do not promise remote payment or a particular payout method. |
For an unresolved refusal, the USA.gov state consumer-protection directory [S32] identifies the relevant public office. A complaint can document the problem and prompt review; it does not guarantee payment.
If the state does not require a cash-out
The absence of a general statutory threshold does not prevent an issuer from offering a more generous policy. Ask about voluntary redemption first. If cash is unavailable, consider whether the balance can be applied to a purchase you already planned, combined with another permitted payment method or transferred to someone who can use it under the terms.
Selling a card to a third party is a different transaction. The price can be lower than the balance, and acceptance of tiny or already registered balances is not guaranteed. Compare the actual net proceeds and terms; do not confuse a discounted resale offer with the issuer paying a statutory redemption claim.
Unclaimed-property recovery is different again. Abandonment statutes determine when certain obligations are reported or transferred to a state. They do not automatically require a merchant to hand over a small balance on demand. Nor does every gift card become claimable through an unclaimed-property office. The state entries distinguish those regimes wherever they are the main gift-card provisions found.
What merchants and digital-card providers should build
For a gift-card operator, a balance-check page is also the moment a customer discovers that the remaining value may be awkward to spend. A useful design should let the customer identify the product, see an accurate remaining balance and find the appropriate redemption or support route. This is an editorial recommendation, not a claim that every state mandates a particular interface.
The balance screen is part of the problem
A second Accenture table presented by Statista uses a wider base of 1,501 respondents: 36% wanted easier balance checks and 35% wanted reminders about unused value. Those preferences focus attention on making a remainder visible before the customer decides what to do with it. They do not measure the effect of design changes. [S145]
F06. Customers wanted visibility and reminders
Requested gift-card improvements, United States, 2024. Accenture online survey of 1,501 respondents.
%
Tap or hover for details. All values are also available in the data table.
Source
Multiple responses allowed. Labels paraphrased. Exact fieldwork dates are not specified in Statista’s metadata. This base differs from the 483-person unused-balance group. These preferences do not establish awareness of cash-redemption rights.
Show data tableHide data table
| Category | Respondents |
|---|---|
| Easier balance checks | 36% |
| Unused-balance reminders | 35% |
| Easier use online and in-store | 32% |
| More ways to spend | 32% |
| More personalisation | 30% |
| Upgrade to premium options | 26% |
| Clearer instructions | 23% |
| Better technical support | 23% |
A system based only on “state + balance” will miss important cases. It may also need original face value, reloadability, whether and how a purchase occurred, whether the code became an account balance, and the product's funding or promotional status. Massachusetts makes the distinction between balance and redemption history obvious; Maine and Oregon show why account treatment matters; Texas shows why transaction channel matters.
Keep the legal rule separate from the payment workflow. A right to redeem should not be described as proof that every cash-out must happen through the same channel. Train customer-service teams to distinguish a qualifying remainder request from a routine return, and make the reason for any denial specific enough to review.
An operational dashboard can track requests, qualifying claims, completion times, refusals by reason and unresolved cases. Those would be company measurements—not figures this investigation has established for the market. Publishing such data would help answer an important question that consumer balance surveys leave open: how usable are the rights that already exist?
Every state, with the rule and the source
The entries below cover all 50 states alphabetically. Dollar thresholds apply only when the relevant law covers the card and transaction. “No general right identified” is a bounded research finding. Source references distinguish statutes, enacted laws, agency guidance and statutory reproductions.
T04. The 50-state index
Show data tableHide data table
| State | Finding | Reviewed authority |
|---|---|---|
| No general threshold identified | Source [S33] | |
| No general threshold identified | Source [S01] | |
| No general threshold identified | Source [S34] | |
| No general threshold identified | Source [S35] | |
| < $15 | Source [S02] | |
| ≤ $5 | Source [S03] | |
| < $5 | Source [S04] | |
| No general threshold identified | Source [S36] | |
| No general threshold identified | Source [S37] | |
| No general threshold identified | Source [S38] | |
| < $5 | Source [S05] | |
| No general threshold identified | Source [S39] | |
| No general threshold identified | Source [S40] | |
| No general threshold identified | Source [S41] | |
| No general threshold identified | Source [S42] | |
| No general threshold identified | Source [S43] | |
| No general threshold identified | Source [S44] | |
| No general threshold identified | Source [S45] | |
| < $5 | Source [S06] | |
| No general threshold identified | Source [S46] | |
| ≥90% used / reloadable ≤ $5 | Source [S07] | |
| No general threshold identified | Source [S47] | |
| No general threshold identified | Source [S48] | |
| No general threshold identified | Source [S49] | |
| No general threshold identified | Source [S50] | |
| < $5 | Source [S08] | |
| No general threshold identified | Source [S51] | |
| No general threshold identified | Source [S52] | |
| No general threshold identified | Source [S53] | |
| < $5 | Source [S09] | |
| No general threshold identified | Source [S54] | |
| < $5 | Source [S10] | |
| No general threshold identified | Source [S55] | |
| No general threshold identified | Source [S56] | |
| No general threshold identified | Source [S57] | |
| No general threshold identified | Source [S58] | |
| < $5 | Source [S11] | |
| No general threshold identified | Source [S59] | |
| < $1 — qualified wording | Source [S12] | |
| No general threshold identified | Source [S60] | |
| No general threshold identified | Source [S61] | |
| No general threshold identified | Source [S62] | |
| < $2.50 | Source [S13] | |
| No general threshold identified | Source [S63] | |
| < $1 | Source [S14] | |
| No general threshold identified | Source [S64] | |
| < $5 | Source [S15] | |
| No general threshold identified | Source [S65] | |
| No general threshold identified | Source [S66] | |
| No general threshold identified | Source [S67] |
Continue reading for free.
Create your account or sign in to get unlimited access.
No payment required. Newsletter signup is optional.
Already registered? Sign inIn this article

Oliver Reed
Oliver Reed covers industry acquisitions, investment and market research for Gift Card News.