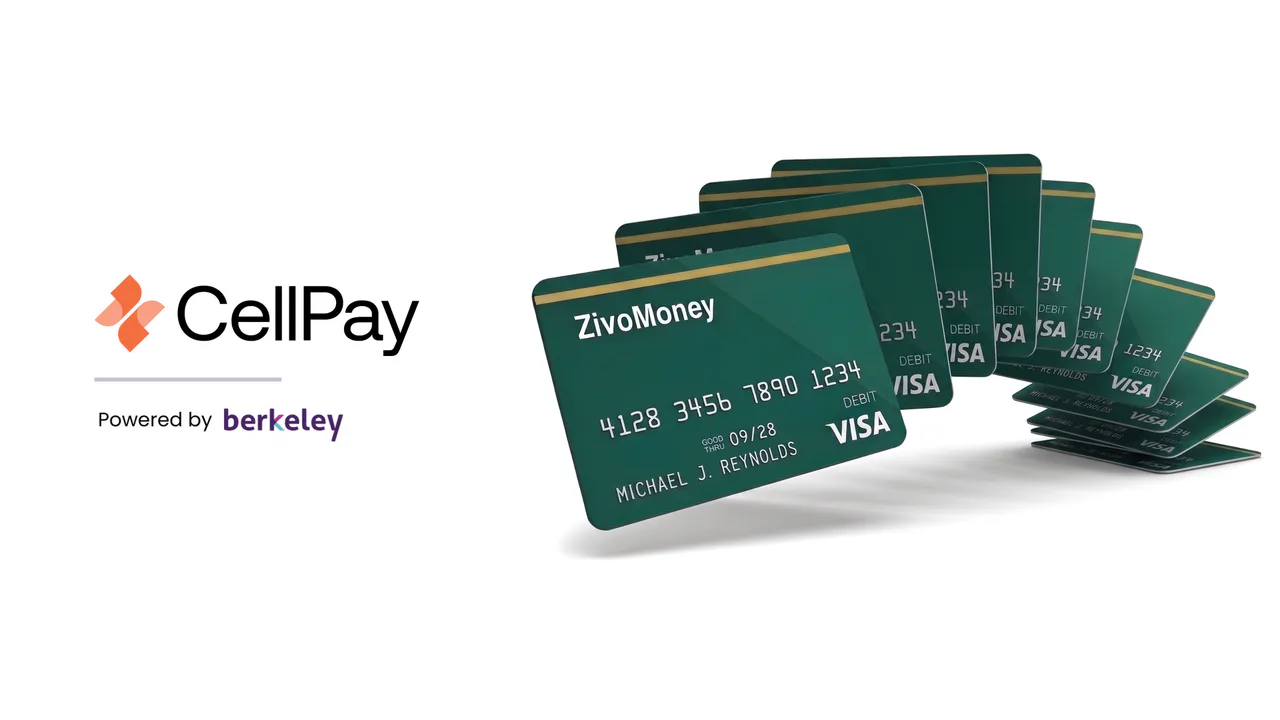
CellPay has added a cash-funded mobile-wallet card to its prepaid distribution business, launching ZivoMoney on September 10 with Berkeley Payment Solutions as programme manager. Customers buy the single-load Visa prepaid card at a participating retailer and can add it to Apple Pay or Google Pay on the purchase day, according to the launch announcement. [S01]
The product connects cash accepted at a retail counter with online and contactless spending. For merchants and prepaid distributors, that creates a way to sell digital payment access through an existing physical distribution relationship, without requiring the customer to fund the purchase from a bank account.
Cash-to-wallet access and its distribution limits
The launch release invokes financial exclusion, but the original FDIC survey gives a more specific historical context. In June 2023, it estimated that 4.2% of US households were unbanked and 14.2% were underbanked. The latter group already had bank accounts but had used specified nonbank services. Neither category is a forecast of people who will buy this prepaid card, and access to digital payments is not absent for every unbanked household. [1] [3]
The historical banking-access context for a cash-funded card
FDIC estimates for two distinct groups of US households in June 2023.
% of US households
Tap or hover for details. All values are also available in the data table.
Source
June 2023 household estimates, published November 2024, not a 2026 product forecast or count of people. Unbanked means no household member had a checking or savings account at a bank or credit union. Underbanked households had an account but used at least one of eight defined nonbank services during the preceding 12 months. Weighted survey of 29,483 households; overall response rate 49%. These selected categories are not the complete distribution and do not measure ZivoMoney demand, customer eligibility or gift-card market size.
Show data tableHide data table
| Category | Published value |
|---|---|
| Unbanked households | 4.2 % of US households |
| Underbanked households | 14.2 % of US households |
The FDIC figures come from a weighted Census Current Population Survey supplement with 29,483 household responses and an overall response rate of 49%. Its technical notes describe survey weighting, nonresponse adjustment and imputation. The results concern households in 2023, rather than individual customers or the 2026 prevalence of cash-only payment. They do not establish product adoption. [3] [4]
Berkeley's account of the launch describes a maximum load of $999.99, no reloads and no ATM withdrawals. The card can be used where Visa debit is accepted in the United States. Berkeley also says no bank account or credit check is required. These terms make it a finite prepaid spending product rather than an ongoing transaction account. [S02]
Fees vary by participating retailer and are disclosed before purchase, the companies say. The launch materials do not give a single nationwide purchase price. That leaves the retailer's quoted fee as a material part of the customer's decision alongside the card's load limit and spending restrictions.
The public ZivoMoney site, checked on October 19, opens a card-access portal requiring card number, expiry and CVV. It repeats the issuer, non-reloadable design and $999.99 maximum balance, but does not expose a public fee schedule in that view. No card details were entered; the launch’s claim of retailer-specific fee disclosure therefore remains distinct from an independently checked price. [5]
Sunrise Banks is the issuer, under a Visa licence, while Berkeley provides programme management. Those roles are distinct from CellPay's customer proposition and distribution: the product brings together a retail-facing platform, an issuing bank and a programme operator. [S02]
CellPay is also offering an API through which retailers, marketplaces and financial technology businesses can embed the prepaid card in their own services. The company presents this as a route to distribute wallet-ready cards without assembling a separate card programme. The release does not name additional API customers or disclose integration pricing. [S01]
Founded in 2016 and based in Stafford, Texas, CellPay distributes prepaid wireless, bill-payment, gift-card and prepaid-card products. The company says it serves more than 1,000 retail merchant locations. That is the reach of its broader business; the release does not establish that every location offers ZivoMoney.
The launch is relevant to the gift-card distribution market because an established seller of gift and prepaid products is adding another stored-value option and a route for third-party distribution. ZivoMoney is described by its providers as a single-load prepaid card. The announcement does not position it as a retailer gift card or disclose a gifting-specific feature.
The commercial proposition will depend on participating outlets, disclosed fees and the usefulness of same-day wallet access for cash-paying customers. The providers have announced the product and its operating model, but have not released ZivoMoney-specific sales, active-card or adoption figures.
In this article
Daniel Brooks
Daniel Brooks covers payment networks, financial technology, payment security, gift card fraud and PCI DSS for Gift Card News.