ampliFI Loyalty Solutions is arguing that financial institutions should make rewards more visible in everyday spending, combining gift card redemption with cashback and purchase-linked use of points. Its April 22, 2026 commentary promotes a mix of options rather than the removal of cash rewards. [S01]
The business question behind that position is whether a reward programme can influence which card a customer reaches for next. A point balance has already created a promise to the cardholder; a useful redemption can make the institution’s side of that bargain more apparent.
A specialist serving the card issuer
ampliFI Loyalty Solutions emerged from the 2018 carve-out of Augeo FI. Its company history identifies Mike Knoop as the executive who led that separation and became chief executive. The business serves financial institutions seeking stronger relationships with their cardholders, bringing reward technology and engagement services to the issuer’s programme. [S02]
That role differs from a merchant selling its own gift card. The financial institution owns the card relationship, while ampliFI Loyalty Solutions supplies part of the experience around earning and using rewards. A catalogue card is one destination for the points, not the payment card on which the customer originally earned them.
For the provider, encouraging a wider range of redemptions supports demand for its integrations and ongoing programme services. For the institution, the potential benefit lies in maintaining customer attention between account opening and the next purchase. Neither benefit follows automatically from adding another button to a rewards page.
Several paths out of a points balance
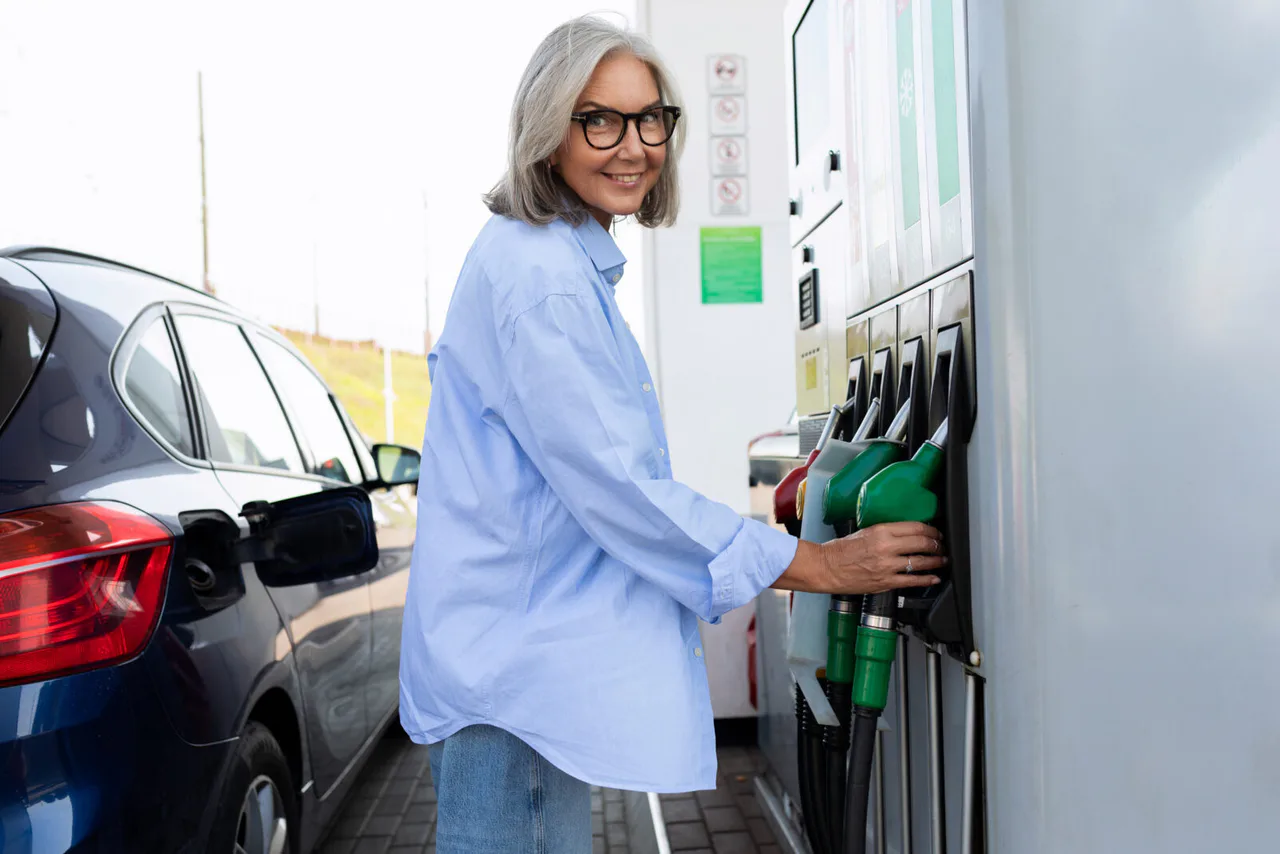
The company’s product page describes Pay With Points as a statement credit following an eligible purchase, alongside Fuel With Points at participating pumps and Checkout With Points in-store. Gift cards offer a catalogue-based alternative; charitable donations and cashback remain in the mix. [S03][S01]
The distinction is about when the customer decides to use value. A catalogue redemption asks the cardholder to leave the immediate purchase journey and select a separate reward. A purchase-linked option puts the choice beside an expense the customer already understands. Both can be useful, but they solve different moments of friction.
A lower barrier to redeeming may also change the sponsor’s cost pattern. If more members use their balances sooner, a programme cannot assess the change only by celebrating higher engagement. It must consider how the cost of delivering those rewards compares with any additional, profitable card use.
Interchange is a starting point, not the result
ampliFI Loyalty Solutions says purchase-linked redemption can preserve the original card transaction while allowing control of point value and redemption cost. It also argues that an active redemption is more noticeable than automatic cashback. These are the provider’s economic and behavioural propositions, not independently demonstrated outcomes in the April article. [S01]
The relevant distinction for an issuer is between earning transaction revenue and retaining a margin after funding the reward and operating the programme. Additional usage is commercially valuable only to the extent that the associated income exceeds those costs. Shifting existing loyal users to a more expensive redemption route would not establish incremental value.
The April commentary supplies no programme-level comparison showing that its proposed mix produces that net gain. [S01] It nevertheless identifies the competitive pressure clearly: rewards have to remain useful enough to be remembered, while institutions need evidence that the attention changes card behaviour rather than merely increasing redemption expense.
In this article
Maya Bennett
Maya Bennett covers customer loyalty, employee rewards and incentive programmes for Gift Card News.