A gift card begins as a promise: the recipient will choose something later. What happens when later never arrives is a question of customer behavior, accounting estimates, contracts and law. This data investigation follows that money through consumer surveys, company filings and academic evidence, and separates reported results from the scenarios used to explain them.
The core research cutoff is 15 September 2026, with Statista data additions reviewed on 16 September 2026. The investigation reviews 14 companies and includes 24 interactive figures and 36 tables. Survey years and company fiscal years remain visible throughout. Source codes in square brackets refer to the annotated bibliography at the end.
What gift card breakage means
A gift can become revenue without becoming a purchase
A gift card starts as a promise. Someone gives up cash today so another person can choose a purchase later. The complication is the interval between those two moments: value can sit on a card, move into an app, be spent in pieces, be lost, or remain usable long after an accountant has recognized some of it as revenue.
This investigation asks four questions: how much value remains unused; how much companies actually recognize as breakage; what evidence supports the estimates; and which party is legally entitled to the residual. Those questions need different datasets. Mixing them produces large, memorable numbers that say less than they appear to.
The central finding is a visibility gap. Public filings can reveal substantial recognized amounts, but they do not provide a complete census of permanent consumer loss. Survey balances include money people still intend to spend. Financial statements apply estimates across many generations of cards. Contract terms and local law determine whether an issuer, a program partner, the purchaser, the recipient, or a public unclaimed-property administrator ultimately receives value.
This is document-based reporting. No interviews were conducted and no private transaction ledger was supplied. Corporate statements are presented as their disclosures; survey answers as self-reports; litigation as attributed allegations or settlements; and analytical scenarios as illustrations. Widely circulated headline estimates are treated as research leads and checked against the underlying evidence before being presented as findings.
T01. Five questions that sound similar but measure different things
| Question | Correct measure | What it cannot establish |
|---|---|---|
| How much is sitting unused? | Outstanding face value at a stated date | Whether it will never be spent |
| How much will never be redeemed? | Ultimate non-redemption for a defined issuance cohort | The current-year accounting entry |
| How much was recognized this year? | Reported breakage income/revenue for that fiscal period | A cohort abandonment rate without matched loads |
| How much did the issuer earn? | Program profit after relevant costs, tax and contractual shares | Profit from the breakage revenue line alone |
| Who gets the residual? | Applicable liability, legal entitlement and contract waterfall | Ownership from possession of cash alone |
The vocabulary determines the result
An unused balance is a stock measured at a point in time. Breakage recognition is a flow measured over a period. A breakage rate is a ratio requiring a defined numerator, denominator and observation horizon. None is interchangeable with the others.
The physical or digital card is also distinct from the obligation. Replacing an expired card may leave its funds intact. Recognizing estimated breakage need not cancel the customer’s redemption right. The most useful analysis follows the monetary obligation across systems, rather than treating a card status field as the final economic outcome.
T02. A working dictionary
| Term | Meaning in this study | Critical boundary |
|---|---|---|
| Face value issued | Value activated or promised to the recipient | May differ from cash paid after discounts or bonuses |
| Outstanding face balance | Value remaining on live instruments | Can exceed the accounting carrying liability |
| Contract liability | Book obligation associated with future goods/services | May already reflect proportional breakage |
| Ultimate breakage | Estimated cohort value never redeemed | Estimate until sufficiently resolved; legal entitlement separate |
| Recognized breakage | Amount recorded in the current accounts | Can include revisions relating to older cards |
| Float | Timing benefit from holding money before settlement | Not the same as ownership of unredeemed principal |
| Escheat / remittance | Transfer to a state under unclaimed-property rules | Cannot simply be treated as merchant breakage |
| Cash redemption | Return of qualifying residual value to the holder | Thresholds and product exceptions vary |
| Fraud loss | Value stolen or diverted | Can happen through successful redemption |
| Non-claim / non-activation | Reward never claimed or activated | Must be separated from post-activation non-spend |
A $100 card has more than one clock
Consider an illustrative $100 card sold at face value, with no fees, returns or escheat obligation. Its initial sale supplies cash but creates an obligation. If reliable evidence supports $8 of ultimate breakage, expected customer redemption is $92. After $46 has been redeemed, half that expected use has happened; proportional recognition records $4 of breakage. The remaining customer face balance is $54, while the remaining book liability is $50.
That difference is the heart of the story. An accounting estimate can move faster than the legal extinguishment of an individual customer right. It is therefore unsafe to say that recognizing breakage proves that a named card was abandoned.
The example abstracts from discounts, multi-party settlement, costs and tax. It explains a proportional recognition mechanism; it does not tell an issuer which accounting standard or legal treatment applies to a real program. [M1]
F01. An accounting liability can fall below the live face balance
USD
Tap or hover for details. Select a series above to show or hide it.
ILLUSTRATIVE: $100 issuance, 8% expected ultimate breakage; no expiry or legal cancellation assumed.
Explore the data table
| Category | Remaining face value | Carrying liability |
|---|---|---|
| Issue | 100 USD | 100 USD |
| Half expected use | 54 USD | 50 USD |
| Expected use complete | 8 USD | 0 USD |
T03. Illustrative lifecycle: face balance versus carrying liability
| Stage | Cash collected cumul. | Redeemed cumul. | Breakage recognized cumul. | Remaining face | Book liability |
|---|---|---|---|---|---|
| Issue | $100 | $0 | $0 | $100 | $100 |
| Half expected redemption | $100 | $46 | $4 | $54 | $50 |
| Expected redemption complete | $100 | $92 | $8 | $8 | $0 |
Illustrative, not a forecast. A residual redemption right may survive accounting recognition. [M1]
What consumer surveys reveal
Fewer Americans reported unused value, but holders had larger balances
The strongest recoverable U.S. survey series covers 2021–2024. Prevalence fell from 51% to 43%, an eight-percentage-point difference, while the conditional mean rose from $116 to $244. These are repeated cross-sections, not the same people or the same cards followed over time. [U01] [U02] [U03] [U04]
The underlying questionnaires concern gift cards, vouchers and store credit. The 2024 coverage includes general-purpose cards and airline or food-delivery vouchers. The 2024 median holder balance was $100, far below the mean: a typical-holder narrative based only on $244 would obscure the distribution. [U05]
A useful denominator check is 0.43 × $244 = $104.92 per adult, using rounded published inputs and including adults with no unused value. The $244 figure is neither a per-card average nor an average for every adult. The national extrapolation is the publisher’s estimate; the public release does not supply enough microdata to construct an independent uncertainty interval. No newer original Bankrate survey was located for this study.
The survey gives two different views of the same unused-value stock. Fewer adults reported holding it in 2024 than in 2021, while the average among holders was higher. Neither observation tells us how much an individual recipient ultimately lost: the people, cards and new gifts entering each survey can change. [U01] [U04] [U05]
F02. The share of adults holding unused value declined across survey vintages
Measure: % of U.S. adults.
%
Tap or hover for details. All values are also available in the data table.
SURVEY: repeated cross-sections; no statistical-significance or causal claim. Not the share of dollars never redeemed.
Explore the data table
| Category | Adults holding unused value |
|---|---|
| 2021 | 51% |
| 2022 | 47% |
| 2023 | 47% |
| 2024 | 43% |
F03. The average unused balance among holders increased
USD
Tap or hover for details. All values are also available in the data table.
SURVEY: conditional on holding unused value. Does not track an issuance cohort.
Explore the data table
| Category | Mean balance among holders |
|---|---|
| 2021 | 116 USD |
| 2022 | 175 USD |
| 2023 | 187 USD |
| 2024 | 244 USD |
F04. National headlines describe outstanding value, not annual breakage
USD billion
Tap or hover for details. All values are also available in the data table.
SURVEY-BASED EXTRAPOLATIONS: approximate published totals; no independently derived error bars.
Explore the data table
| Category | Publisher’s outstanding-value estimate |
|---|---|
| 2021 | 15 USD billion |
| 2022 | 21 USD billion |
| 2023 | 23 USD billion |
| 2024 | 27 USD billion |
T04. Original U.S. survey vintages
| Year | Adults with unused value | Mean among holders | Published outstanding estimate | All-adult mean, derived |
|---|---|---|---|---|
| 2021 | 51% | $116 | About $15bn | $59.16 |
| 2022 | 47% | $175 | About $21bn | $82.25 |
| 2023 | 47% | $187 | About $23bn | $87.89 |
| 2024 | 43% | $244 | About $27bn | $104.92 |
Nominal USD; cards, vouchers and store credit. Survey estimates, not audited balances or annual breakage. [U01] [U02] [U03] [U04]
T05. How the surveys were conducted
| Year | All respondents | Fieldwork | Known holder subsample |
|---|---|---|---|
| 2021 | 2,387 | 30 Jun–2 Jul 2021 | 1,225 |
| 2022 | 2,372 | 27–29 Jul 2022 | Not stated in release |
| 2023 | 2,446 | 20–22 Jun 2023 | Not stated in release |
| 2024 | 2,373 | 19–21 Aug 2024 | 1,010 |
YouGov online adult samples with weighting; nonprobability-panel design. These panel estimates do not support an invented simple-random-sampling margin of error. [U01] [U02] [U03] [U04]
Who holds unused value, and what people say happened to it
Different demographic cuts answer different questions. The generation chart compares dollar balances only among holders. The income chart measures how common unused value is within each income group. Neither alone establishes which group permanently loses the most money.
Statista also publishes the 2024 generation breakdown shown in F05. Its values—$142 for Gen Z, $332 for millennials, $255 for Gen X and $227 for baby boomers—come from the same Bankrate/YouGov survey already cited here. The original release remains the source for the holder-only denominator and survey method; the additional publication does not supply a second estimate of unredeemed money. [ST01] [U04]
Lifetime experiences also differ from the present stock: the 2024 survey recorded expiry, lost cards and business closures. The categories overlap. Their percentages cannot be added, and they are not the fractions of issued value lost each year. [U05]
Plans to redeem are weaker evidence than observed redemption. In the 2022 survey, 45% of holders expected to use all their unused value within a year and 30% most of it. Without following the same instruments, later aggregate surveys cannot tell whether those plans failed: old cards can be spent while new ones arrive. [U02]
F05. Generation differences concern balances among holders
USD
Tap or hover for details. All values are also available in the data table.
SURVEY 2024: conditional holder means; not per card, not permanent loss, and no significance test supplied. Statista reproduces this same Bankrate/YouGov survey; it is not an independent observation.
Explore the data table
| Category | Mean unused balance |
|---|---|
| Gen Z | 142 USD |
| Millennials | 332 USD |
| Gen X | 255 USD |
| Baby boomers | 227 USD |
F06. Unused value was more common in higher-income households
Measure: % within household-income group.
%
Tap or hover for details. All values are also available in the data table.
SURVEY 2024: prevalence, not the share of gift-card dollars abandoned.
Explore the data table
| Category | Adults reporting unused value |
|---|---|
| Under $50,000 | 35% |
| $50,000–79,999 | 44% |
| $80,000–99,999 | 47% |
| $100,000+ | 55% |
T06. Lifetime loss experiences are overlapping responses
| Experience | Share of all adults |
|---|---|
| Ever let a card expire | 20% |
| Ever lost a card | 17% |
| Business closed before use | 12% |
| At least one of these | 34% |
Self-reported experience at any time; not annual incidence or dollar-weighted breakage. [U05]
A reported obstacle is not an ultimate breakage rate
Accenture’s 2024 US Holiday Shopping survey adds a different kind of evidence: people’s explanations for leaving a balance unused. In the table published by Statista, 483 respondents with unused balances could select several reasons. Forgetting the card and having access to only a few brands or stores each drew 34%; 25% said the value was too small to bother using. [ST02]
F07. Consumers report several reasons for leaving a balance unused
All 12 reported reasons from the 2024 US survey. The base is people with an unused balance.
% of respondents with an unused balance
Tap or hover for details. All values are also available in the data table.
SURVEY 2024: Accenture data published by Statista; US online survey, n=483. Multiple responses allowed. No dollar threshold, share of outstanding money or ultimate non-redemption rate is measured. Labels shortened for display.
Explore the data table
| Category | Selected this reason |
|---|---|
| Limited brands or stores | 34 % of respondents with an unused balance |
| Forgot about the card | 34 % of respondents with an unused balance |
| Could not find items to buy | 28 % of respondents with an unused balance |
| No time to use it | 28 % of respondents with an unused balance |
| Unappealing available options | 28 % of respondents with an unused balance |
| Value too small to bother | 25 % of respondents with an unused balance |
| Only one redemption channel | 23 % of respondents with an unused balance |
| Technical redemption problems | 23 % of respondents with an unused balance |
| Expired before use | 22 % of respondents with an unused balance |
| Insufficient flexibility | 20 % of respondents with an unused balance |
| Sign-up required | 18 % of respondents with an unused balance |
| Lost the card | 17 % of respondents with an unused balance |
The ranking does not divide unused cards into separate piles. A person could report a small balance, an inconvenient channel and a forgotten card together. The 23% citing technical difficulties and the 23% citing a single redemption channel cannot therefore be added into a 46% failure rate. Nor does a reported obstacle establish that the money was permanently lost.
These are also different questions from Bankrate’s lifetime experiences in T06. Accenture asks a group holding unused balances why value went unspent; Bankrate asks adults whether specified events ever happened. Even the superficially matching lost-card percentages have different populations. The 25% small-value response gives direct evidence that size can matter, but supplies no universal cutoff below $1, $2 or $3. [ST02] [U05]
T07. Intentions for the next twelve months, 2022
| Planned use of unused value | Share of holders |
|---|---|
| All | 45% |
| Most | 30% |
| A few | 16% |
| None | 9% |
Plans, not tracked outcomes. 71% held at least one instrument a year old; that is not 71% of dollar value. [U02]
A newer snapshot still separates waiting from giving up
CivicScience’s January 2025 reporting, reproduced by Statista, distinguishes several unused-card positions among adults who typically buy or receive gift cards. Eleven percent reported many unused cards, 29% a few, and a further 21% selected the answer that they planned to spend them in the near future. Thirty-nine percent reported none. [ST03] [ST07]
F08. Some unused cards still come with a plan to spend
2025 snapshot among adults who typically buy or receive gift cards.
% of respondents
Tap or hover for details. All values are also available in the data table.
SURVEY SNAPSHOT: CivicScience reporting published 7 January 2025, reproduced by Statista. Categories concern people and plans, not dollars. The population differs from Bankrate’s all-adult ownership measure and its unused-value-holder intentions sample. No tracked redemption outcome is implied.
Explore the data table
| Category | Response share |
|---|---|
| Many unused cards | 11 % of respondents |
| A few unused cards | 29 % of respondents |
| Unused, with plans to spend soon | 21 % of respondents |
| No unused cards | 39 % of respondents |
The 21% with near-term plans must not be relabeled as a breakage rate, and the other unused-card categories do not establish an intention never to spend. This snapshot also cannot validate or refute the 2022 plans in T07: different respondents, timing, response options and populations are involved. A credible estimate of ultimate non-use still needs to follow a defined set of obligations over time.
International headlines need their original questions
Ireland’s 2025 consumer research is unusually specific about its denominator. Among 649 respondents who had received Christmas-2024 vouchers, 77% said they had used the full value, 22% had not and 1% did not know. The not-full category includes partial spending; calling it never redeemed would alter the finding. Interviews took place in October 2025. [U10]
The Australian and British examples below are useful context, but cannot be combined into a cross-country breakage league table. The studies differ in instrument scope, time horizon, sample and outcome. A pandemic-expiry episode, current unused holdings and lifetime loss are not competing estimates of the same quantity.
The Irish question also marks the boundary of the evidence. A respondent who had spent nearly all a voucher and a respondent who had spent none could both answer that its full value had not been used. The 22% result identifies incomplete redemption among recipients; it cannot reveal the percentage of voucher money still outstanding. [U10]
F09. Not fully redeemed does not mean never redeemed
Measure: % of recipients.
%
Tap or hover for details. All values are also available in the data table.
IRELAND SURVEY, October 2025; Christmas-2024 recipients n=649; full sample n=1,012. Includes a range of voucher products.
Explore the data table
| Category | Share of voucher recipients |
|---|---|
| Full value used | 77% |
| Not fully used | 22% |
| Do not know | 1% |
T08. Selected international evidence
| Place / source | Observation | Limit |
|---|---|---|
| Ireland / CCPC 2025 | 22% of recipients had not used full value | Includes partial use; finite observation horizon |
| Australia / Finder, Dec 2024 fieldwork | 33% held unused cards; 21% reported ever losing value | Stock prevalence versus lifetime experience |
| Australia / Australian Treasury, 2012 | Industry-informed breakage assessment above 3%, below 8% | Historical; before later expiry reform |
| UK / Which? 2020 | Among expiring-voucher subgroup: 49% auto-extension, 15% on request, 36% none | Lockdown-specific; not an annual breakage rate |
What company filings and research show
What public-company filings actually disclose
The table below covers 14 public companies selected for relevant disclosures. Six disclose separate amounts in the reviewed notes; others describe a policy, provide a liability or combine breakage with redemption. This is an evidence map, not a ranking of all issuers or a representative industry sample.
Reported carrying liabilities are not uniformly measured consumer face balances. Some are net of estimated breakage or fees; Starbucks’ roll-forward includes loyalty Stars. Fiscal labels and year-end dates also differ. Large balances beside missing breakage figures should prompt questions, not invented estimates.
Revenue classification can differ too: Walmart places breakage in membership and other income, while several retailers include it in sales. An analysis that searches only the sales line could miss relevant recognition. [C09]
Even apparently similar labels can cover different products. DICK'S discusses gift cards alongside merchandise credits and added acquired Foot Locker liabilities during the year. Walmart separately discusses reward-related income. Keeping those boundaries visible prevents a convenient comparison from becoming a claim about a uniform gift-card market. [C18] [C09]
F10. Six disclosed amounts illustrate scale, not an industry ranking
USD million
Tap or hover for details. All values are also available in the data table.
Latest reviewed annual periods: Brinker FY2026, others FY2025. Product scope and year-ends differ; see disclosure table.
Explore the data table
| Category | Separately disclosed breakage |
|---|---|
| Starbucks | 222.400 USD million |
| DICK'S Sporting Goods | 41.300 USD million |
| Chipotle | 27.877 USD million |
| Cheesecake Factory | 24.500 USD million |
| Brinker | 10.300 USD million |
| Red Robin | 5.243 USD million |
T09. Selected latest annual disclosures, USD million
| Company | Fiscal label | Period end | Breakage | Carrying liability | Scope / caveat |
|---|---|---|---|---|---|
| FY2025 | 2025-09-28 | 222.4 | 1,751.7 | Cards + Stars liability; card breakage | |
| FY2025 | 2026-01-31 | 41.3 | 305.548 | Cards / merchandise-credit policy; acquired Foot Locker | |
| FY2025 | 2025-12-31 | 27.877 | 174.6 | Gift cards; loyalty separate | |
| FY2025 | 2025-12-30 | 24.5 | 212.859 | Reassessment affects 2025 | |
| FY2026 | 2026-06-24 | 10.3 | 52.8 | Liability net of breakage and fees | |
| FY2025 | 2025-12-28 | 5.243 | 24.096 | Gift cards; loyalty separate | |
| FY2025 | 2025-12-31 | Not separately disclosed | 5,600 | Gift-card liability | |
| FY2026 | 2026-01-31 | Not separately disclosed | 2,941 | Deferred gift-card revenue | |
| FY2025 | 2026-01-31 | Not separately disclosed | 1,197 | Net of estimated breakage | |
| FY2025 | 2026-02-01 | Immaterial; unquantified | 1,100 | Liability approximate; breakage immaterial | |
| FY2026 | 2026-05-31 | Not separately disclosed | 636.7 | Deferred gift-card revenue before separately reported USD 31.6m deferred gift-card discounts; redemptions and breakage combined | |
| FY2025 | 2025-12-30 | Not separately disclosed | 448.744 | Activations net of third-party fees | |
| FY2026 | 2026-01-31 | Not separately disclosed | 235 | Breakage not separately quantified | |
| FY2025 | 2025-12-30 | Not separately disclosed | 16.06 | Opening-balance revenue is not breakage |
Dates are issuer fiscal year-ends. These rows must not be summed into a national market estimate. Missing is not zero. [C01] [C18] [C13] [C14] [C15] [C20] [C08] [C09] [C04] [C06] [C11] [C10] [C07] [C21]
Starbucks reveals both the scale and the denominator problem
Starbucks’ card breakage series combines company-operated and licensed-store amounts. It increased from $144.6m in FY2020 to $222.4m in FY2025, with a decline in FY2024. That is recognized card revenue, not a measured cohort-loss percentage. [C01] [C02] [C03]
The FY2025 roll-forward reports $15,245.8m of additions and a $1,751.7m closing balance, but combines stored-value cards with loyalty Stars. Dividing card breakage by that addition row would mix scopes. The product also permits reloads, so it is not a pure non-reloadable gift-card benchmark. [C01]
F11. Starbucks recognized card breakage across two store channels
USD million
Tap or hover for details. Select a series above to show or hide it.
COMPANY DISCLOSURES: annual recognition, not cohort ultimate losses. The FY2020–2025 total is not a present outstanding balance. FY2021 contained 53 weeks; FY2020 and FY2022 contained 52 weeks. The two disclosed components are shown side by side; their sum is total reported card breakage.
Explore the data table
| Category | Company-operated | Licensed |
|---|---|---|
| 2020 | 130.3 USD million | 14.3 USD million |
| 2021 | 164.5 USD million | 16.6 USD million |
| 2022 | 196.0 USD million | 16.7 USD million |
| 2023 | 196.1 USD million | 18.9 USD million |
| 2024 | 187.6 USD million | 20.0 USD million |
| 2025 | 200.4 USD million | 22.0 USD million |
T10. A combined roll-forward cannot supply a clean card-load denominator
| FY2025 component | USD million |
|---|---|
| Opening cards + Stars liability | 1718.7 |
| Cards + Stars additions | 15245.8 |
| Redemptions + breakage | -15199.5 |
| Other change | -13.3 |
| Closing cards + Stars liability | 1751.7 |
Arithmetic: 1,718.7 + 15,245.8 - 15,199.5 - 13.3 = 1,751.7. Mixed scope is preserved. [C01]
The income effect of an estimate change is visible in the footnotes
Cheesecake Factory’s FY2025 breakage was $24.5m, including $17.3m of additional recognition from reassessed redemption patterns. A separate $7.9m gift-card inventory write-down partly offset it; the company’s more precise pre-tax gift-card adjustment, net of the inventory write-down, was $9.396m. Compared with $187.285m operating income, that net adjustment is about 5.0%, an analytical comparison rather than a restated profit measure. [C14]
Chipotle reported $27.877m of breakage in 2025, up from $7.760m in 2024 and $1.162m in 2023. Its $20.1m year-over-year increase is disclosed, but is not identified here as an isolated estimate-change amount. The evidence supports a large recognition increase, not an assertion about its entire cause. [C13]
Brinker supplies the other direction: FY2024 breakage declined by $5.4m, which management attributed primarily to an estimate anticipating higher redemption. Its FY2025 audit treated breakage as a critical audit matter. Accounting estimates can reduce as well as increase reported income. [C17] [C16]
The two restaurant examples show why a breakage line needs its surrounding notes. Cheesecake Factory reported additional recognition alongside an inventory charge; Brinker described lower recognition after expecting more redemption. Reading the revenue entry alone would miss either the offsetting cost or the direction of the underlying estimate. [C14] [C17]
F12. Restaurant disclosures show different recognition paths
USD million
Tap or hover for details. Select a series above to show or hide it.
COMPANY DISCLOSURES: issuer fiscal years differ slightly. Lines compare recognized amounts, not abandonment rates.
Explore the data table
| Category | Chipotle | Cheesecake Factory | Red Robin |
|---|---|---|---|
| 2023 | 1.162 USD million | 7.300 USD million | 9.874 USD million |
| 2024 | 7.760 USD million | 7.300 USD million | 7.930 USD million |
| 2025 | 27.877 USD million | 24.500 USD million | 5.243 USD million |
T11. What the disclosures do and do not explain
| Company | Verified statement | Do not infer |
|---|---|---|
| Additional $17.3m recognition after reassessment; $9.396m pre-tax gift-card adjustment, net of the inventory write-down | The full $24.5m was new cash or net profit | |
| Breakage increased approximately $20.1m year over year | All of the increase was an estimate revision | |
| 2024 decline primarily reflected higher expected redemption | Falling breakage necessarily means weaker card sales | |
| A 50bp assumption change implies about $3.5m FY2025 income sensitivity | 50bp is the company’s actual breakage rate |
A transparent roll-forward still needs careful labels
Brinker separates sales, redemptions and breakage in its roll-forward, giving readers more visibility than a single combined reduction. Even here, the liability is net of breakage and unamortized third-party fees. Its reported sales row should not automatically be treated as gross face issued. [C15]
Darden reports activations and a combined redemption/breakage reduction. Its FY2026 $751.9m reduction cannot be separated into purchases and breakage from that row alone. Target’s $849m addition is even easier to misread: it is current-year cards still unredeemed, net of breakage, not total annual gift-card sales. [C11] [C04]
F13. Brinker’s separately disclosed breakage fell before leveling off
USD million
Tap or hover for details. All values are also available in the data table.
COMPANY DISCLOSURES: fiscal-year amounts. FY2024 decline primarily reflected changed expected redemption.
Explore the data table
| Category | Breakage |
|---|---|
| 2023 | 16.5 USD million |
| 2024 | 11.1 USD million |
| 2025 | 10.0 USD million |
| 2026 | 10.3 USD million |
T12. Brinker gift-card roll-forward, USD million
| Fiscal year | Opening | Sales as reported | Redemptions | Breakage | Other | Closing |
|---|---|---|---|---|---|---|
| 2023 | 83.9 | 127.1 | 121.7 | 16.5 | 0.2 | 73 |
| 2024 | 73 | 122.2 | 119.5 | 11.1 | 0.2 | 64.8 |
| 2025 | 64.8 | 122.8 | 120.4 | 10 | 0 | 57.2 |
| 2026 | 57.2 | 127.4 | 121.3 | 10.3 | -0.2 | 52.8 |
Closing = opening + reported sales - redemptions - breakage + other; small rounding differences may occur. [C15] [C16] [C17]
T13. Three common extraction errors
| Filing row | What it is | What it is not |
|---|---|---|
| Darden FY2026: $751.9m | Combined redemptions and breakage | Standalone breakage or standalone redemptions |
| Target FY2025: $849m | Current-year cards still unredeemed, net of breakage | All card sales during the year |
| Best Buy: over 90% within a year | Timing of redemptions and associated recognition | Proof that over 90% of every issuance cohort is redeemed |
The research record is strongest on disclosure, weaker on universal rates
An original Journal of Accountancy review of 167 available 2006 filings found only eight companies separately reporting a breakage amount. Its disclosure categories overlap; they are not stages in a funnel. That historical snapshot documents opacity, but cannot establish today’s disclosure prevalence. [A03]
Gregory G. Kaufinger and Chris Neuenschwander’s 2025 paper, Exploring Voluntary Disclosure of Gift Card Breakage: Insights From Agency and Signaling Theory, examines 79 U.S. retail and restaurant firms across FY2013–2022: 790 firm-year observations. Table 2 records disclosure of a breakage amount in 173 of 395 observations before FY2018 and 194 of 395 afterward—43.8% versus 49.1%, an increase of 5.3 percentage points. These are reporting frequencies, not redemption rates. [A01]
The frequently repeated 2–4% retail breakage range comes from Audit Analytics’ July 2017 discussion of breakage revenue relative to gift-card sales. It is historically attributable; it is not a current, representative cohort benchmark. [A09]
The widely quoted fifteenfold result comes from a narrower model: 17 firms that changed disclosure behavior, totaling 170 firm-year observations. Table 9 reports an ASC 606 coefficient of 2.716 and an odds ratio of 15.116. Odds are probability divided by one minus probability; a fifteenfold odds ratio is not a fifteenfold probability. This selected-sample association neither establishes managerial intent nor measures consumer losses. [A01]
F14. Separate dollar disclosure was rare in a 2006 filing sample
companies out of 167
Tap or hover for details. All values are also available in the data table.
HISTORICAL ORIGINAL ANALYSIS: categories overlap; not a mutually exclusive distribution or current disclosure census.
Explore the data table
| Category | Companies |
|---|---|
| Any gift-card information | 113 companies out of 167 |
| Revenue-recognition policy | 99 companies out of 167 |
| Gift-card liability separately | 51 companies out of 167 |
| Breakage policy | 53 companies out of 167 |
| Breakage dollar amount separately | 8 companies out of 167 |
T14. Reading research without upgrading its claim
| Source | What it supports | What it cannot establish |
|---|---|---|
| JofA 2007 filing review | Historical disclosure scarcity | Today’s breakage volume |
| 2025 disclosure study | Observed reporting frequencies; selected-sample odds ratio | Causal effects or consumer breakage rates |
| Audit Analytics 2017 | A dated reported 2–4% accounting ratio | A 2026 universal cohort rate |
| Milliman 2022 | Methods and program-specific estimation issues | An observed 10% industry benchmark |
Psychology can explain spending choices without measuring abandonment
Chelsea Helion and Thomas Gilovich’s 2014 paper, Gift Cards and Mental Accounting: Green-lighting Hedonic Spending, combines hypothetical choices, a laboratory experiment and store transactions. In the experiment’s 38-person analysis, the gift-card group spent 76% on hedonic items versus 47% for cash. Participants had to spend at least $5; this examined purchase composition, not abandonment. [A05]
The same paper followed 332 Cornell campus-store customers who used both gift and credit cards. Their average hedonic spending shares were 52% and 21%, respectively. The comparison holds the customer constant, but payment choice was observational and departments proxy for individual products. It does not measure permanently unredeemed value. [A05]
Spending composition and eventual redemption are separate outcomes. Evidence that a gift card encourages an indulgent purchase cannot establish a universal balance threshold or a deadline after which the money will never be spent. Estimating either requires tracking comparable balances over time, with redemption, refunds and expiry recorded separately.
F15. Gift-card spending tilted toward hedonic departments in one study
Measure: % of spending.
%
Tap or hover for details. All values are also available in the data table.
OBSERVED STUDY COMPARISON: matched-tender subset n=332, Cornell campus store. Department classification is a proxy; not a breakage study.
Explore the data table
| Category | Average hedonic spending share |
|---|---|
| Gift card | 52% |
| Credit card | 21% |
A new 2026 study finds high non-use in a different product
Yixuan Liu, Hua Zhang and Eric Zou’s February 2026 working paper analyzes 4,616,004 consumers and 96,829 merchants on one Chinese merchant-prepayment platform during 2023–2024. Credits never expire. Approximately 40% of prepaid value remained unused after a year; treating it as permanent non-redemption requires inference beyond the observed follow-up. [A14]
For prepayments more than 12 months old at merchants still active in the final week of 2024, approximately 17% were wholly unspent and 17% fully spent. The remainder was partially used. These are transaction shares, not shares of monetary value. The reported median merchant ROI of 5.5 equals breakage divided by bonus incentives actually paid, minus one; it is not a full operating-profit measure. [A14]
These bonus-bearing credits were bought for personal use, limiting comparisons with U.S. gift cards. [A14]
F16. Partial use dominated one Chinese merchant-prepayment sample
Prepayments more than 12 months old at merchants active in the final week of 2024.
%
Tap or hover for details. All values are also available in the data table.
February 2026 working paper, Figure 4D. Approximate transaction shares; 66% is the derived remainder. Not consumer or value shares.
Explore the data table
| Category | Prepayment transactions |
|---|---|
| Wholly unspent | 17% |
| Partially spent | 66% |
| Fully spent | 17% |
Measuring breakage and its economics
The wrong denominator can manufacture a trend
Dividing this year’s breakage by this year’s loads can be useful as a clearly labeled accounting-intensity ratio. It is generally not a cohort breakage rate: the recognized amount can relate to older cards while the denominator contains newly sold cards whose redemption is barely underway.
The reverse mistake appears during a sales slowdown. Recognition from older cohorts can remain high while new loads shrink, mechanically raising the ratio. A change in that ratio does not by itself show that customers became more forgetful. Loyalty balances, refunds and promotional credits can further contaminate the denominator.
A sound cohort estimate matches cards issued in the same period and follows their redemptions to a common age, while separating refunds, cash returns, transfers and legally remittable balances. The same calendar month can contain mature Christmas cards and fresh promotional rewards, each with a very different remaining life.
F17. Unchanged recognition can produce very different apparent rates
Measure: %.
%
Tap or hover for details. All values are also available in the data table.
ILLUSTRATIVE: same $5m recognition in all periods. These are not cohort breakage rates.
Explore the data table
| Category | Recognized breakage / current loads |
|---|---|
| Year A | 5.0% |
| Year B | 2.5% |
| Year C | 10.0% |
T15. Illustrative denominator trap
| Period | Recognized breakage | New loads | Annual breakage / loads | Valid inference |
|---|---|---|---|---|
| Year A | $5m | $100m | 5.0% | Accounting intensity only |
| Year B | $5m | $200m | 2.5% | New loads doubled; ultimate breakage unknown |
| Year C | $5m | $50m | 10.0% | New loads fell; ultimate breakage unknown |
How to estimate breakage without declaring living cards dead
The data should be organized by issuance cohort and age since issuance. Start with money, not just card counts: a mostly exhausted $100 card and an untouched $100 card are not equivalent exposures. Preserve partial redemptions and distinguish first use from final depletion.
Milliman describes multiplicative development, additive future-redemption estimates and mature-cohort analogues. It explicitly rejects a universal curve: its approximately 10% tail illustration is hypothetical. Different channels, denominations and disruptions can change both timing and ultimate use. [R1]
For a more advanced model, a mixture-cure formulation can separate eventual non-use from the timing of use among eventual redeemers. That sophistication does not eliminate the central identification problem: a card that has not been used by the end of a short sample may be a slow redeemer, not a permanent non-redeemer. Extrapolating a long tail requires assumptions, mature history and sensitivity analysis.
For partial spending, a multi-state or marked-event model is more informative than a first-redemption survival curve alone. Track untouched, partly used, exhausted, refunded, remitted and otherwise resolved states. Preserve migration between cards or wallets so a technical replacement is not mistaken for a new customer obligation. These are proposed analytical practices, not claims that a particular company uses them.
F18. Slow redemption and higher ultimate breakage are different stories
Measure: % of original face redeemed.
%
Tap or hover for details. Select a series above to show or hide it.
ILLUSTRATIVE curves: R(t)=ultimate redemption × (1-exp(-t/scale)). Month on x-axis. Not fitted to observed gift-card data. Selected observation ages are equally spaced on this categorical axis; the intervals between ages are unequal.
Explore the data table
| Category | Fast: 8% ultimate breakage | Slow: 8% ultimate breakage | Fast: 20% ultimate breakage |
|---|---|---|---|
| 1 months | 14.12% | 4.97% | 12.28% |
| 3 months | 36.20% | 14.12% | 31.48% |
| 6 months | 58.16% | 26.08% | 50.57% |
| 12 months | 79.55% | 44.77% | 69.17% |
| 24 months | 90.31% | 67.75% | 78.53% |
| 36 months | 91.77% | 79.55% | 79.80% |
| 60 months | 92.00% | 88.72% | 80.00% |
| 84 months | 92.00% | 91.13% | 80.00% |
T16. Models answer different questions
| Approach | Useful question | Main weakness |
|---|---|---|
| Cohort redemption triangle | How do older cohorts develop after the same age? | Mix changes and a weak tail history |
| Additive future-use model | How much additional value is expected after today? | Tail assumptions can dominate |
| Mature-cohort analogue | What do sufficiently old similar cards imply? | Older cards may no longer be representative |
| Survival / cure model | How much non-use is delay versus eventual non-use? | Cure share poorly identified with short follow-up |
| Partial-balance state model | What happens after first use and small residuals? | More data and event-reconciliation demands |
| Scenario range / stress test | How sensitive is liability to credible alternative assumptions? | Does not substitute for an evidence-based central estimate |
The measurement system an advanced investigation needs
The decisive dataset is a reconciled ledger linking issuance, funding, redemption, adjustments and final disposition. It should permit both a financial roll-forward and a customer-outcome analysis. A daily balance export without event history cannot establish whether residuals vanished through legitimate redemption, migration, refund, fees or data loss.
Use separate tables for economic face value and accounting carrying value. Give every record a currency and retain original currency until a transparent conversion rule is chosen. A bank settlement, a merchant order and a gift-card redemption may be three records of one economic event, not three separate uses of money.
Validation should begin with conservation: opening face plus loads and reinstatements minus redemptions, refunds, valid fees and transfers out must equal closing face after explained adjustments. Then reconcile the accounting roll-forward separately, including breakage and estimate revisions. Failures in either identity should block publication of an aggregate rate.
T17. Minimum analytical fields
| Field group | Required information | Why it matters |
|---|---|---|
| Instrument | Stable tokenized ID, parent/reissue ID, program, currency | Avoid duplicate instruments and broken migrations |
| Issue and funding | Issued/activated timestamps, face, cash paid, bonus component | Separate promised value from paid value |
| Distribution | Consumer purchase, employer reward, promotion, channel | Comparable cohorts and incentives |
| Events | Timestamp, event type, monetary delta, reversal linkage | Accurate partial redemption and reconciliation |
| Balance | Opening, closing, live face, carrying liability | Distinguish consumer rights from books |
| Legal classification | Jurisdiction evidence, expiry terms, remittance class | Entitlement and exceptions |
| Experience | Delivery, claim, activation, decline reason, reminder exposure | Identify access friction without guessing motive |
| Model | Cohort, model version, expected ultimate use, recognized breakage | Reproduce changes and audit estimate revisions |
T18. Quality tests that change the conclusion
| Test | Failure example | Analytical consequence |
|---|---|---|
| Reconciliation | Closing balances do not equal event sums | No reliable ultimate non-use estimate |
| Duplicate handling | Replacement card counted as new issuance | Inflated denominator |
| Reversal handling | Refund restores value but not issuance history | Apparent late redemption anomaly |
| Follow-up horizon | Six-month cohort compared with five-year cohort | False trend |
| Cohort mix | Promotional cards pooled with purchased cards | Misleading benchmark |
| Right censoring | Still-open cards labeled permanently unused | Upward bias in breakage |
| Unit consistency | Card counts mixed with monetary face | Rates answer different questions |
| Legal boundary | Remittable balance counted as corporate income | Overstated entitlement |
A small estimate change can create a large income effect
For a simple eligible cohort, let F be issued value, b the expected ultimate breakage fraction and R cumulative redemptions. Expected ultimate redemption is F(1-b); cumulative proportional breakage is R × b/(1-b), subject to the appropriate recognition constraints and an ultimate cap. Current-period recognition is the change from the previously recognized cumulative amount.
In the illustrative $1m cohort below, $460,000 has been redeemed. Raising the estimated breakage rate from 8% to 12% increases cumulative recognized breakage from $40,000 to about $62,727, without another customer transaction. Reducing the estimate to 4% lowers it to about $19,167. That is why changes in estimation require an explanation separate from sales performance. [M1]
The derivative R/(1-b)^2 describes local sensitivity to b in this simplified formula. It is a mathematical sensitivity, not a probability or permission to book an amount. Actual recognition also depends on the applicable standard, legal entitlement, data quality and constraints on reversal risk.
F19. Recognition moves even when redemptions do not
USD
Tap or hover for details. All values are also available in the data table.
ILLUSTRATIVE: x-axis expected ultimate breakage (%); fixed $1m issuance and $460k redemption.
Explore the data table
| Category | Cumulative recognized breakage |
|---|---|
| 2% | 9,387.76 USD |
| 4% | 19,166.67 USD |
| 6% | 29,361.70 USD |
| 8% | 40,000.00 USD |
| 10% | 51,111.11 USD |
| 12% | 62,727.27 USD |
T19. Illustrative estimate sensitivity at the same redemption level
| Assumed ultimate rate | Cumulative breakage | Carrying liability | Change from 8% case |
|---|---|---|---|
| 2% | $9,388 | $530,612 | $-30,612 |
| 4% | $19,167 | $520,833 | $-20,833 |
| 6% | $29,362 | $510,638 | $-10,638 |
| 8% | $40,000 | $500,000 | $+0 |
| 10% | $51,111 | $488,889 | $+11,111 |
| 12% | $62,727 | $477,273 | $+22,727 |
F=$1m; R=$460,000. Rounded display only; underlying calculations retain precision. [M1]
Float is a timing benefit, not another name for breakage
Breakage concerns principal that will not be redeemed. Float concerns the interval before cash must be spent or settled. A fully redeemed program can still have a financing benefit; a program with high breakage may have little usable float if funds are restricted or the economics belong to another party.
For an analytical estimate, separate average funds actually available for investment, the realized net yield, custody restrictions, settlement timing and who receives interest. Multiplying every outstanding consumer balance by a headline interest rate assumes answers to all of those questions.
The scenario below illustrates that distinction. It uses a hypothetical $100m average balance, investable shares of 0%, 50% and 100%, and assumed net annual yields. It excludes taxes and operational costs. Nothing here estimates Starbucks, a bank issuer or any named program’s interest income. [M1]
F20. Available funds determine the financing benefit
USD million per year
Tap or hover for details. Select a series above to show or hide it.
ILLUSTRATIVE: x-axis net yield (%); $100m average balance. The 0%-available case is zero at every yield.
Explore the data table
| Category | 50% available | 100% available |
|---|---|---|
| 0% | 0.0 USD million per year | 0.0 USD million per year |
| 1% | 0.5 USD million per year | 1.0 USD million per year |
| 2% | 1.0 USD million per year | 2.0 USD million per year |
| 3% | 1.5 USD million per year | 3.0 USD million per year |
| 4% | 2.0 USD million per year | 4.0 USD million per year |
| 5% | 2.5 USD million per year | 5.0 USD million per year |
T20. Illustrative annual float benefit on a $100m average balance
| Investable share | At 1% net yield | At 3% net yield | At 5% net yield |
|---|---|---|---|
| 0% | $0 | $0 | $0 |
| 50% | $0.5m | $1.5m | $2.5m |
| 100% | $1m | $3m | $5m |
For reward buyers, non-use can mean paying for an outcome that never happened
For a merchant selling its own paid gift card, breakage can contribute to financial results. For an employer or promotional sponsor buying a reward, the same non-use may mean its intended benefit never reached the recipient. The cash recipient and the party seeking engagement are not necessarily the same business.
A reward also has more than one drop-off point: approved, delivered, claimed, activated, first spent and fully spent. A dashboard that stops at email delivery cannot measure realized reward value. An unclaimed reward link is not automatically a funded card balance, and a funded unused card is not automatically revenue for the distributor.
Ask when the sponsor is charged, whether unused value is returned, who holds the funds, what happens after expiry, and how reports distinguish non-claim from post-activation residuals. Those are contract questions. Marketing labels such as no breakage or pay on use require an operational definition before they can be compared.
F21. Unreturned unused value raises the sponsor’s cost per redeemed dollar
USD per redeemed USD
Tap or hover for details. All values are also available in the data table.
ILLUSTRATIVE: sponsor pays $100k face + $2k fees; unused funds are not returned. X-axis ultimate unused value (%). No assumption about lawful ownership of residuals.
Explore the data table
| Category | Sponsor cost / redeemed value |
|---|---|
| 0% | 1.020 USD per redeemed USD |
| 5% | 1.074 USD per redeemed USD |
| 10% | 1.133 USD per redeemed USD |
| 20% | 1.275 USD per redeemed USD |
| 30% | 1.457 USD per redeemed USD |
T21. Questions that reveal the reward economics
| Commercial feature | Question to resolve | Consequence |
|---|---|---|
| Funding trigger | At order, delivery, claim, activation or spend? | Determines sponsor exposure before use |
| Residual entitlement | Who receives unused principal and under which law? | Determines whether non-use is margin or a payable |
| Return mechanism | Automatic refund, credit, replacement or no return? | Changes effective campaign cost |
| Expiry | Which object expires: link, card credential or funds? | Determines whether access can be restored |
| Fees | Issue, decline, inactivity, replacement, FX or support? | Can consume recipient value independently of non-use |
| Reporting | Face issued, delivered, redeemed and remitted separately? | Allows a reconciled result |
| Program roles | Issuer, processor, distributor and sponsor liabilities? | Avoids assuming the platform owns breakage |
Recovering value and separating fraud
A merchant should measure the cost of recovery as well as its benefit
Reducing breakage can improve customer outcomes while having an ambiguous short-term profit effect. Redemption consumes goods or services; it can also drive incremental spending and later contribution. The right comparison is incremental contribution against a credible no-intervention counterfactual, not total sales made by everyone who used a card.
Consumer preferences can help choose which recovery measures to investigate. In another Accenture 2024 US table published by Statista, 36% selected simpler balance checks, 35% regular reminders for unused balances, and 32% easier redemption across online and in-store channels. More versatile use also drew 32%. Statista reports 1,501 respondents for this question, a different base from the 483 unused-balance respondents in F07. [ST04]
F22. Consumers ask for easier access to existing value
Requested improvements to the gift-card experience, rather than measured effects of a recovery campaign.
% of surveyed US consumers
Tap or hover for details. All values are also available in the data table.
SURVEY 2024: Accenture data published by Statista; US online survey, n=1,501. Multiple answers possible. Neither incremental redemption nor profit was measured. The one-point gap between the first two choices is descriptive, not proof of statistical significance. Labels shortened for display.
Explore the data table
| Category | Selected this improvement |
|---|---|
| Simpler balance checks | 36 % of surveyed US consumers |
| Reminders for unused balances | 35 % of surveyed US consumers |
| Easier online/in-store redemption | 32 % of surveyed US consumers |
| More versatile use | 32 % of surveyed US consumers |
| More personalization | 30 % of surveyed US consumers |
| Option to upgrade the gift card | 26 % of surveyed US consumers |
| Clearer usage instructions | 23 % of surveyed US consumers |
| Better technical support | 23 % of surveyed US consumers |
The findings provide candidates for action, not a revenue forecast. A reminder may bring a planned purchase forward, recover value that would otherwise remain idle, or prompt a purchase that would have happened anyway. Better balance visibility may resolve an access problem without producing an additional sale. Only a comparison that measures the intervention’s incremental effect can distinguish these outcomes; that is why the recovery calculation and design in T22–T23 remain necessary.
The companion article What people want when they check a gift card balance examines the balance-checking task and provides official checking routes for 20 brands and programs.
For a simplified closed-loop program, recover D of previously unredeemed face value. Let c be the variable cost fraction of fulfilling that value, U incremental cash spending caused by the intervention, m its contribution margin, H incremental future contribution and K campaign cost. Incremental contribution is mU + H - cD - K. This holds the original card-sale cash fixed and ignores tax, discounts and capacity constraints.
An illustrative recovery of $10,000, variable cost of 60%, margin of 40% on extra spending and $1,000 campaign cost requires $17,500 of incremental extra spending if there is no later contribution. With $5,000 of demonstrable future contribution, the requirement falls to $5,000. The calculation is an analytical break-even, not an industry benchmark. [M1]
T22. Illustrative recovery break-even
| Incremental future contribution H | Extra spending U required | Interpretation |
|---|---|---|
| $0 | $17,500 | Immediate contribution must carry all cost |
| $2,000 | $12,500 | Some cost offset by later business |
| $5,000 | $5,000 | Repeat contribution changes the case |
| $7,000 | $0 | Later contribution covers assumed cost |
T23. An experiment that can distinguish access improvement from unprofitable subsidy
| Design element | Measure | Interpretation |
|---|---|---|
| Random assignment | Reminder / balance-visible group versus eligible control | Separates intervention effect from motivated redeemers |
| Primary customer outcome | Additional face value redeemed or returned by fixed age | Measures actual benefit reaching holders |
| Primary business outcome | Incremental contribution including fulfillment and campaign cost | Avoids treating recovered face as free profit |
| Longer horizon | Later contribution and late redemption in both groups | Tests acceleration versus genuinely incremental use |
| Guardrails | Declines, fraud, complaints, unsubscribes and cash returns | Identifies harmful side effects |
| Inference | Confidence interval clustered at recipient or household where relevant | Avoids false precision from repeated cards |
| Pre-registration | Population, exclusions, horizon and stopping rules | Limits result selection after seeing the data |
A drained card and an abandoned card are opposite ledger events
Fraud can leave a customer with no usable value because someone else redeemed it. Breakage arises from value not redeemed. A customer complaint that a card has no balance cannot establish which occurred. The distinction matters both for restitution and for claims about issuer profitability.
The FTC describes Consumer Sentinel as an administrative collection of unverified reports, not a consumer survey. Its statistics therefore need their own reporting and coverage caveats. They should not be added to survey unused balances or recognized corporate breakage to create one grand total of gift-card waste. [R3]
Statista’s 2024 fraud tables illustrate the distinction in monetary terms: they reproduce 41,120 reports and $212 million in reported losses from the FTC’s payment-method data. The original category is “Gift Card or Reload Card.” It is broader than retailer gift cards and does not isolate theft from a card that its owner intended to keep. [ST05] [ST06] [ST08]
T24. Reported fraud involving a payment method is not breakage
| FTC Consumer Sentinel, 2024 | Reported figure | What the figure means |
|---|---|---|
| Reports listing Gift Card or Reload Card | 41,120 | Administrative fraud reports identifying that payment method; not verified cases or unique victims. |
| Reported monetary losses in the category | $212 million | Rounded published reported-loss sum, using the FTC’s loss inclusion rules; not outstanding unused balances or issuer breakage revenue. |
The FTC limits the dollar amounts in this table to reports of losses from $1 through $999,999; the report count is a separate payment-method measure. Consumer Sentinel is not a probability sample or a complete census, and the table should not be treated as a US-only national estimate. A card used to pay a scammer may have been fully redeemed. Such a loss belongs in a fraud analysis, not in the same numerator as value that nobody redeemed. [ST08] [R3]
A proper investigation follows the card event log: activation, authorized and disputed transactions, fees, refunds and replacement links. It also asks who bore the loss. A reimbursed victim, a merchant chargeback and a program reserve expense describe different economic outcomes.
T25. Classifying what happened to the value
| Observed problem | Possible mechanism | Evidence needed |
|---|---|---|
| Card has zero balance | Legitimate redemption, theft, fee or transfer | Event ledger and transaction authorization |
| Card will not work | Technical expiry, blocked merchant, authentication or exhausted funds | Decline reason and replacement policy |
| Reward email unopened | Delivery or engagement failure | Delivery/claim logs and funding trigger |
| Old positive balance | Delayed use or ultimate non-use | Cohort history and current legal status |
| Book liability reduced | Breakage recognition, refund, remittance or adjustment | Financial roll-forward and accounting policy |
| Retailer insolvent | Obligation may be impaired or restricted | Proceeding-specific redemption and creditor treatment |
Accounting rules, consumer rights and enforcement
Which law applies depends on what was issued
A paid retailer card, an open-loop gift card, a promotional reward and a reloadable prepaid account can follow different rules. Open-loop acceptance alone is not an exemption from U.S. federal gift-card protections. Qualifying promotional/reward instruments have specific disclosure requirements; their label is not sufficient. [L06] [L07]
For covered U.S. instruments, the federal funds-expiry floor is generally five years from issuance or last load, as applicable, or the later card expiry. Qualifying inactivity/service fees require a year of inactivity, disclosure and no more than one such fee a month. State protections may be stronger. The assertion that all dormancy fees were eliminated is inaccurate. [L06]
The following matrices are a selected-jurisdiction comparison, not a worldwide or fifty-state compliance inventory. Finite minimum-validity periods do not measure actual redemption speed and do not rank total consumer protection.
The accounting choice starts with the issuer's promise. An obligation to supply its own goods differs from an obligation to pay another merchant when a cardholder spends. The IFRS Interpretations Committee's 2016 decision turned on that payment obligation, even though the customer could not redeem the card for cash. [L04]
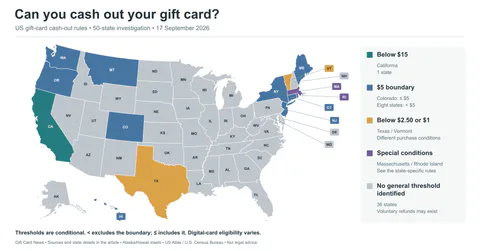
Small-balance rules also change the possible outcome of an unused card. California's test is a balance below $15, while Ireland's EUR1 remedy depends on a contract preventing later use and permits a replacement voucher. The amount alone does not identify the holder's remedy. [L08] [L15]
F23. Selected minimum-validity rules range from three to nine years
years
Tap or hover for details. All values are also available in the data table.
LEGAL MINIMUMS, with product/date exceptions. California and ordinary Canadian prepaid funds are not plotted as zero; UK has no uniform floor established here.
Explore the data table
| Category | Covered minimum |
|---|---|
| Australia | 3 years |
| New Zealand | 3 years |
| U.S. federal | 5 years |
| Ireland | 5 years |
| Massachusetts | 7 years |
| New York | 9 years |
T26. Accounting scope is not universal
| Obligation | Framework | Recognition condition |
|---|---|---|
| Advance for issuer’s own goods/services | IFRS 15 B44–B47 | Expected entitled breakage proportional to exercised rights, subject to the variable-consideration constraint; otherwise when remaining exercise becomes remote |
| Equivalent U.S. revenue contract | ASC 606-10-55-46–49 | Proportional/remote framework; remittable amounts remain liabilities |
| Eligible U.S. prepaid financial liability | ASC 405-20 | Proportional derecognition subject to significant-reversal constraint; otherwise when remaining exercise becomes remote. Escheatable portions and specified other liabilities are excluded. |
| Specified third-party merchant prepaid arrangement | IAS 32 / IFRS 9 | Financial-liability classification; not automatically IFRS 15 |
| IFRS financial liability | IFRS 9 3.3.1 | Obligation discharged, cancelled or expired; expected non-use alone does not establish extinguishment |
T27. Selected U.S. cash-redemption and validity rules
| Place | Validity protection | Small-balance rule | Key scope limit |
|---|---|---|---|
| California | Covered certificates generally cannot expire | Strictly below $15; operative 1 Apr 2026 | Specified multi-seller and promotional exceptions |
| New York | Covered-certificate expiry floor 9 years; funds separately protected | Strictly below $5 on request | Cash rule excludes open-loop and promotional |
| Massachusetts | At least 7 years; indefinite if expiry not properly disclosed | Nonreloadable: >=90% redeemed; reloadable: partial use leaves <=$5 | Do not collapse distinct tests into one threshold |
T28. Selected international rules
| Place / product | Rule | Limit |
|---|---|---|
| Ireland / covered vouchers | Minimum 5 years or no expiry; no forced one-shot use | E-money, loyalty and other exclusions |
| Ireland / qualifying residual | EUR1 or more with contractual bar to reuse: reimbursement or replacement | Not an unconditional right to cash |
| Australia / covered cards | Minimum 3 years; prominent expiry; restricted post-supply fees | From 1 Nov 2019; promotional/reloadable and other exceptions |
| New Zealand / covered cards | Minimum 3 years from 16 Mar 2026 | Specified loyalty, free, top-up and other exclusions |
| Canada / federally regulated prepaid | Ordinary funds cannot expire; credential can | Promotional funds exception; separate institutional scopes |
| Canada / retailer cards | Most do not expire | Provincial/territorial exceptions matter |
| United Kingdom / vouchers | Contractual expiry possible; fairness/transparency rules | No uniform statutory floor established by reviewed sources |
[L14] [L15] [L16] [L17] [L18] [L19] [L20] [L21] [L22]
T29. Who can claim unredeemed value?
| Question | Verified distinction |
|---|---|
| General U.S. first-priority rule | Creditor’s last known address in debtor records; not universally point of purchase |
| General second-priority rule | Debtor’s incorporation state when first-priority rule does not apply; special statutes can alter treatment |
| Delaware covered gift/stored value | Generally five years after latest specified owner-interest event; measure refers to maximum issuer cost |
| Delaware loyalty exclusion | Statutory definition, not the word reward, controls |
| Remittable balance | Remains a liability under relevant revenue guidance; not an accounting election to keep it |
The Supreme Court source explains general priority rules; its MoneyGram-specific holding is not a gift-card holding. [L10] [L11] [L01] [L02]
T30. Tax can run on a separate timetable
| Constructed eligible advance-payment example | Receipt year | Following year |
|---|---|---|
| Cash collected | $1m | $0 |
| Assumed applicable-financial-statement revenue | $600k | Not assumed |
| Tax income under qualifying elected deferral method | $600k | Remaining $400k |
ILLUSTRATIVE federal income-tax timing, not tax due. Eligibility and election requirements matter; sales tax/VAT not modeled. [L24] [M1]
Enforcement shows why an expired balance may not be gone
In July 2026 Ireland’s CCPC announced that JD Sports would reissue 5,604 online cards, representing EUR246,859, after an incorrect one-year expiry. The announced completion deadline is 4 January 2027, after this study’s cutoff. This is an undertaking to restore value, not verification that restoration is complete or that the amount had been booked as breakage. [L23]
In New York, the Attorney General’s 2024 account describes more than $36m recovered from H&M in 2022 and a later settlement with Card Compliant concerning alleged avoidance of unclaimed-property obligations. The exact latter settlement is $4,375,000; the signed agreement says it is a compromise of disputed claims without admission of liability or wrongdoing. These are not criminal convictions or measured consumer breakage rates. [A06] [A07]
The common issue is control over the obligation. A software status change or an intercompany contract does not by itself establish the right to retain the money. A journalist must examine the actual operating arrangement, the applicable legal test and the procedural status of any enforcement claim.
T31. Two cases, two distinct outcomes
| Case | Verified number | Status at cutoff |
|---|---|---|
| JD Sports / Ireland | 5,604 cards; EUR246,859 | Reissue undertaking; deadline 4 Jan 2027 |
| JD Sports average, calculated | EUR44.05 per affected card | 246,859 / 5,604; not an industry average |
| Card Compliant / New York | $4,375,000 settlement | Disputed claims; no admission |
| Settlement allocation | $3,368,750 state; $1,006,250 relator | Allocation, not consumer principal |
National estimates and transparent disclosure
The national total remains a reporting problem
There is no defensible shortcut from a few prominent company disclosures to a national breakage total. The sample is selected by disclosure availability, contains different product scopes and fiscal periods, and excludes many private companies. A sum can describe the selected disclosures; it cannot establish market coverage.
An earlier attempt illustrates the difficulty. A 2020 SSIR viewpoint described an estimated $4.22bn for selected companies in 2017, split into $381m from full disclosers, $755m from hybrid disclosers and $3.085bn from nondisclosers. Most of that estimate was therefore not a directly disclosed standalone amount. The displayed components sum to $4.221bn, with rounding explaining the headline. [R2]
That estimate is historically useful as an example of the transparency problem, not as a measured current total or an audited industry census. Extrapolating nondisclosers requires assumptions that are not interchangeable with the companies’ accounts. Likewise, a survey’s estimate of outstanding consumer balances cannot be relabeled annual corporate revenue.
F24. Most of a widely cited historical estimate depended on nondisclosers
USD million
Tap or hover for details. All values are also available in the data table.
HISTORICAL ESTIMATE in a 2020 viewpoint; not a current measured market total. Categories follow the author’s disclosure classification.
Explore the data table
| Category | 2017 estimated breakage |
|---|---|
| Full disclosers | 381 USD million |
| Hybrid disclosers | 755 USD million |
| Nondisclosers | 3,085 USD million |
T32. What would make a defensible national estimate
| Requirement | Why it is needed |
|---|---|
| Defined product universe | Purchased closed-loop, general-purpose and promotional programs differ |
| Matched time basis | Cohort ultimate loss and annual recognized income are different totals |
| Coverage frame | Know which issuers and private firms are missing |
| Comparable accounting measure | Separate income, contra-expense and contract adjustments |
| Deduplicated issuer/program roles | Avoid counting a platform and its issuer twice |
| Legal disposition | Remove amounts refunded, remitted or contractually owed elsewhere |
| Transparent missing-data model | Show assumptions and sensitivity rather than a single confident number |
What a transparent gift-card disclosure would reveal
The best disclosure would connect the customer promise to the financial result. It would state face issued, cash collected, redemptions, cash returns, legal remittances, remaining face value, carrying liability and recognized breakage. It would explain whether loyalty rewards or promotional instruments are included and identify the portion caused by estimate revisions.
That level of reporting would help several readers at once. Customers could distinguish access failures from actual loss; campaign buyers could see whether rewards reached recipients; analysts could separate sales performance from estimate changes; and policymakers could assess how much value was recovered, rather than counting only legal rules on the books.
A voluntary donation or balance-recovery scheme can be useful, but it must not silently replace the recipient’s rights or a legal duty to remit funds. The defensible question is not whether forgotten balances look available; it is who has authority to direct them and whether the intended beneficiary can still recover value.
T33. Questions for issuers, auditors and reward platforms
| Ask | Evidence that would answer it |
|---|---|
| What fraction is a true cohort estimate? | Matched issuance and ultimate-redemption schedule |
| How much of this year is an estimate change? | Bridge from prior expected redemption to current estimate |
| What happens when an old card is found? | Current redemption policy and accounting treatment |
| Which balances cannot be retained? | Jurisdiction/contract mapping and remittance schedules |
| Is disclosure comprehensive? | Product scope and materiality exclusions |
| Does a reminder change timing or ultimate use? | Controlled study followed over a sufficiently long horizon |
| Who receives interest and residuals? | Custody and economic-sharing clauses |
| Do digital cards reduce permanent loss? | Comparable cohorts with common age and customer mix |
| Who benefits from a donation claim? | Consent, legal authority, transfer evidence and recipient outcomes |
Checking widely circulated breakage claims
Widely repeated claims about unused gift card money often combine different years, products and accounting measures. The comparison below separates the reported evidence from interpretations that change its meaning: a survey balance is not annual revenue, an odds ratio is not a probability multiplier, and association does not establish intent.
T34. Claims that survive, change or fail verification
| Claim reviewed | Verdict | What the evidence establishes |
|---|---|---|
| 43% hold unused value; average $244 | Correct numbers, misdated when called 2026 research | August 2024 survey; mean among holders |
| $23bn paired with 43%/$244 | Mixed vintages | 2023: 47%/$187/~$23bn; 2024: 43%/$244/~$27bn |
| Starbucks $222.4m pure profit | Amount verified; profit label wrong | FY2025 recognized card breakage revenue |
| Amazon $80–110m / below 1% | Unsubstantiated | No separate amount/rate in reviewed FY2025 note |
| Home Depot $35–45m recurring | Unsubstantiated current range | Current note says immaterial; historical catch-up not a run rate |
| All firms must separately disclose exact breakage | Overbroad | Scope and materiality affect disclosure |
| Proportional recognition always required | Incorrect as a universal rule | Remote treatment and financial-liability scopes matter |
| ASC 606 made probability 15 times higher | Odds and probability confused | Table 9: odds ratio 15.116 in 17 firms; not a probability multiplier |
| Weak liquidity proves earnings manipulation | Not established | Disclosure associations do not establish intent |
| CARD Act eliminated all dormancy fees | Incorrect | Qualifying fees remain permitted |
| Before/after spillage proves legal causality | Overstated | Definitions, censoring and other changes confound comparison |
[U01] [U02] [U03] [U04] [C01] [C06] [C08] [A01] [A03] [A09] [A10] [A11] [L01] [L02] [L03] [L06]
Historical billions are not one continuous series
CEB’s original releases projected $1.7bn of spillage in 2012, about 1% of spend in 2013 and less than 1% in 2015. An analysis by the New Jersey Office of Legislative Services describes a definition involving expiry, fees and business closure, and anticipates temporary suppression from the five-year expiry floor. The series therefore cannot be treated as directly comparable to current proportional accounting recognition. [U06] [U17] [U07] [U08]
The approximately $21bn reported in the 2022 consumer survey and $27bn in the 2024 survey estimate outstanding unused balances. Those are stocks of value held at the time of each survey. The earlier spillage estimates concern value not spent under a different definition. Combining the two measures into a single trend would confuse money still available to consumers with money treated as lost or unspent. [U02] [U04] [U08]
T35. A guide to the conflicting national numbers
| Number | Vintage | What it measures |
|---|---|---|
| $1.7bn | 2012 | CEB forecast spillage |
| About 1% | 2013 | CEB spillage estimate relative to spend |
| Less than 1% of $130bn | 2015 | CEB forecast-market context; not an exact $1bn observation |
| About $21bn | 2022 | Outstanding survey estimate |
| About $27bn | 2024 | Outstanding survey estimate |
Methods and limitations
Core research cutoff: 15 September 2026; the Statista additions were reviewed on 16 September 2026. The study uses company filings, original survey releases, regulator materials, full academic papers and attributed secondary data tables. Statista is credited alongside the underlying survey or reporting organization, and republications of the same study are not counted as independent evidence. Publication and access dates are kept separate from observation dates; source fiscal years retain their original labels.
The company sample is purposive, selected for relevant public disclosures, and is not statistically representative. Dollar amounts are nominal and retain their reported currencies. No foreign exchange conversion or inflation adjustment is applied. Missing disclosures remain missing; immaterial is a qualitative statement, not zero. Derived changes use unrounded source values when available.
The charts distinguish observed disclosures, survey estimates, historical research and illustrative scenarios in their captions. Survey means are conditional on their stated populations. Multiple-response categories are not additive. No synthetic customer records are presented as evidence. Model examples teach mechanisms and sensitivity; they do not supply a forecast for any real issuer.
Academic findings are drawn from the full texts linked in the source register, with the February 2026 working-paper version identified explicitly. Every interactive figure includes an expandable data table. Percentages calculated here retain their stated denominators; approximate source values remain approximate. Reproducing arithmetic does not independently validate a survey, company estimate or statistical model.
The unanswered empirical questions are explicit: a current comprehensive national ultimate-breakage total; comparable category-wide breakage rates; causal evidence for a universal small-balance threshold; an issuer-level open-loop entitlement census; and a broadly comparable digital-versus-physical permanent-loss estimate. None is filled with a guessed number.
T36. Evidence labels used throughout
| Label | What it means | Typical limitation |
|---|---|---|
| Company disclosure | Reported in a public financial statement | Estimation and scope are company-specific |
| Survey result | Original consumer research with population stated | Recall, sampling and question wording |
| Regulatory rule | Provision or regulator guidance checked at cutoff | Product and jurisdiction exceptions |
| Attributed enforcement | Government account or settlement document | Allegation, settlement and adjudication differ |
| Academic finding | Findings checked against the full paper and its stated sample | Association may not identify causation |
| Historical estimate | Dated estimate from a named source | Cannot be repurposed as a current census |
| Illustrative scenario | Transparent assumed inputs and arithmetic | Not an observed benchmark or prediction |
Sources and documents
Collapse
- [R1, A08] Milliman: The Drawer of Forgotten Gift Cards (2022). Actuarial methods and illustrative curves; not a measured universal breakage benchmark.
- [R2] Bruce Cahan / SSIR: Using Gift Card Breakage to Democratize Philanthropy (2020). Advocacy viewpoint describing a 2017 estimate; limited methodology and imputation for nondisclosers.
- [R3] FTC: Consumer Sentinel Network Data Book 2024. Administrative consumer complaints, not a probability sample or gift-card breakage census.
- [M1] Study calculations and analytical framework. Original arithmetic and clearly labeled hypothetical scenarios created for this study. No empirical company or customer data are implied.
- [C01] Starbucks FY2025 Form 10-K. Notes 1 and 11
- [C02] Starbucks FY2023 Form 10-K. Notes 1 and 11
- [C03] Starbucks FY2022 Form 10-K. Notes 1 and 11
- [C04] Target FY2025 Form 10-K. Notes 2 and 15
- [C05] Target FY2024 Form 10-K. Note 2
- [C06] Home Depot FY2025 Form 10-K. Revenue note
- [C07] Best Buy FY2026 Form 10-K. Notes 1 and 9
- [C08] Amazon FY2025 Form 10-K. Note 1, Accrued Expenses and Other
- [C09] Walmart FY2026 Form 10-K. Notes 1 and 4
- [C10] Texas Roadhouse FY2025 Form 10-K. Notes 2 and 3
- [C11] Darden FY2026 Form 10-K. Notes 1 and 3; printed pages 56 and 61–62
- [C12] Darden FY2025 Form 10-K. Critical Accounting Estimates and Note 3
- [C13] Chipotle FY2025 Form 10-K. Notes 1 and 3; consolidated income statement; MD&A revenue bridge
- [C14] Cheesecake Factory FY2025 Form 10-K. Notes 1 and 8; MD&A; consolidated income statement
- [C15] Brinker FY2026 Form 10-K. Notes 1 and 2
- [C16] Brinker FY2025 Form 10-K. Notes 1 and 2; auditor critical audit matter
- [C17] Brinker FY2024 Form 10-K. Note 2; MD&A revenue bridge
- [C18] DICK'S Sporting Goods FY2025 Form 10-K. Notes 1 and 7
- [C19] DICK'S Sporting Goods FY2024 Form 10-K. Note 1
- [C20] Red Robin FY2025 Form 10-K. Notes 1 and 3; revenue disaggregation and contract liabilities in Note 3
- [C21] BJ's Restaurants FY2025 Form 10-K. Notes 1,2 and 5
- [U01] Bankrate: U.S. Adults Total $15 Billion in Unused Gift Cards, Vouchers, Store Credits. Primary survey release
- [U02] CreditCards.com: Despite Inflation Concerns, Almost Half of Americans are Holding on to Unused Gift Cards Totaling $21 Billion Nationwide. Primary survey release
- [U03] Bankrate: Nearly Half of US Adults Have at Least One Unused Gift Card; Average Amount is $187. Primary survey release
- [U04] Bankrate: Over 2 in 5 U.S. Adults Have at Least One Unused Gift Card, Totaling About $27 Billion. Primary survey release
- [U05] Survey: 43% of Americans have at least one unused gift card. Primary survey article; same study as U04
- [U06] Gift Card Sales To Top $110 Billion As Card Spillage Declines 20 Percent. Primary researcher press release; forecast
- [U07] 2015 Gift Card Sales To Reach New Peak Of $130 Billion. Primary researcher press release; forecast
- [U08] Fiscal estimate S2235; legislative history of P.L.2015 c.8. Primary official fiscal analysis discussing CEB estimates
- [U10] CCPC Christmas Shopping Research 2025. Primary regulator survey; PDF physical page 18 / printed slide 23
- [U11] £100m lost in expired vouchers during lockdown — how to get yours extended. Primary consumer survey
- [U13] Part IV — Gift card administration, Gift Cards in the Australian Market Report. Primary government review of industry submissions
- [U14] Gift card graveyard: Aussies sitting on $1.25 billion in unused vouchers. Primary commercial consumer survey
- [U15] $1.8 billion languishing on unused gift cards. Primary commercial consumer survey
- [U17] Gift Card Sales To Top $118 Billion As E-Gifting Boosts Growth. Primary researcher press release; estimate
- [A01] Exploring Voluntary Disclosure of Gift Card Breakage: Insights From Agency and Signaling Theory (2025). Full paper; Tables 2 and 9.
- [A03] Accounting for Gift Cards. original filing analysis; historical
- [A05] Gift Cards and Mental Accounting: Green-lighting Hedonic Spending — Helion and Gilovich (2014). Complete published paper, Studies 2 and 3, pp. 389–391.
- [A06] NY Attorney General Card Compliant settlement announcement. government enforcement announcement
- [A07] Card Compliant stipulation and settlement agreement. government-hosted settlement; neither admission liability nor wrongdoing
- [A09] Gift Card Breakage (ASC606). commercial original SEC filing analysis
- [A10] Lost and found: Booking liabilities and breakage income for unredeemed gift cards. accounting explainer historical
- [A11] Gift Card Revenue - Gift or Grief? historical accounting explainer
- [A14] Pay Now, Buy Never: The Economics of Consumer Prepayment Schemes. Full working paper, February 2026; Figure 4D and p. 26.
- [L01] IFRS Foundation, IFRS 15, B44–B47, issued text PDF pp. 47–48 (PDF indices 46–47). primary legal/regulatory/standard-setting text
- [L02] Deloitte DART, 8.8 Customers’ Unexercised Rights—Breakage; reproduces ASC 606-10-55-46–49 and interpretation. accounting firm interpretation with reproduced ASC text
- [L03] FASB ASU 2016-04, ASC 405-20-40-3–4 and 50-2, PDF pp. 10–11 (indices 9–10); checked against current DART text. primary legal/regulatory/standard-setting text
- [L04] IFRIC Update March 2016, final agenda decision, pp. 5–6; IFRS Foundation publication hosted by German standard setter DRSC. primary legal/regulatory/standard-setting text
- [L05] IFRS Foundation, IFRS 9, paragraph 3.3.1. primary legal/regulatory/standard-setting text
- [L06] CFPB, Regulation E §1005.20, definitions, exclusions, fees and expiry. primary legal/regulatory/standard-setting text
- [L07] CFPB, Regulation E §1005.2(b)(3), prepaid-account definition and exclusions. primary legal/regulatory/standard-setting text
- [L08] California Civil Code §1749.5, operative 1 Apr 2026. primary legal/regulatory/standard-setting text
- [L09] California Civil Code §1749.45, product scope. primary legal/regulatory/standard-setting text
- [L10] US Supreme Court, Delaware v. Pennsylvania and Wisconsin, 28 Feb 2023, discussion of Texas v. New Jersey rules at opinion pp. 3–4. primary legal/regulatory/standard-setting text
- [L11] Delaware Code Title 12, §§1130(10), (13), (21), 1133(14). primary legal/regulatory/standard-setting text
- [L12] New York General Business Law §396-i, notably (3-b), (3-c), (5), (5-a), (5-b). primary legal/regulatory/standard-setting text
- [L13] Massachusetts General Laws ch.200A §5D. primary legal/regulatory/standard-setting text
- [L14] CCPC, Gift vouchers, current consumer guidance. primary legal/regulatory/standard-setting text
- [L15] Irish Law Reform Commission, revised Consumer Protection Act 2007, §66B(4)–(5). primary legal/regulatory/standard-setting text
- [L16] Financial Consumer Agency of Canada, Prepaid cards: know your rights, 15 Oct 2025. primary legal/regulatory/standard-setting text
- [L17] ACCC, Gift cards and discount vouchers. primary legal/regulatory/standard-setting text
- [L18] New Zealand Commerce Commission, Gift cards and vouchers, 2026 rule and exceptions. primary legal/regulatory/standard-setting text
- [L19] Canada Bank Act §627.38 (ordinary funds/promotional distinction), plus §627.39 for maintenance charges. primary legal/regulatory/standard-setting text
- [L20] FCAC, Gift cards, 16 Oct 2025. primary legal/regulatory/standard-setting text
- [L21] House of Commons Library, Consumer payments made in advance of receiving goods or services, 23 Mar 2023, p.6. primary legal/regulatory/standard-setting text
- [L22] UK Consumer Rights Act 2015, Part 2, especially §§62 and 68. primary legal/regulatory/standard-setting text
- [L23] CCPC, JD Sports to honour over 5,000 expired vouchers worth almost €250,000, 6 Jul 2026. primary legal/regulatory/standard-setting text
- [L24] Treasury Regulation §1.451-8, especially (c), (c)(9) and examples 14–16, legal text reproduced by Cornell LII. Treasury regulation reproduced by Cornell LII
- [ST01] Statista: mean unused value among holders by generation, 2024. Reproduces the Bankrate / YouGov study already cited as U04; not independent evidence. — Statista / Bankrate / YouGov
- [ST02] Statista: Accenture Holiday Shopping 2024, reasons for unused gift-card balances. US online survey; 483 respondents with unused balances; multiple answers. Published 12 November 2024. — Statista / Accenture
- [ST03] Statista: CivicScience unused gift-card ownership and plans for use. The article uses only the 2025 snapshot. Published 7 March 2025. — Statista / CivicScience
- [ST04] Statista: Accenture Holiday Shopping 2024, requested gift-card improvements. US online survey; 1,501 respondents; multiple answers. Published 12 November 2024. — Statista / Accenture
- [ST05] Statista: reports of gift-card fraud, 2024. The original FTC payment category is Gift Card or Reload Card. Updated 1 September 2026. — Statista / Federal Trade Commission
- [ST06] Statista: reported monetary losses for gift-card fraud, 2024. Original FTC category includes reload cards; this is not gift-card breakage. Updated 1 September 2026. — Statista / Federal Trade Commission
- [ST07] CivicScience: post-holiday gift-card spending and unused-card ownership, 7 January 2025. Defines the ownership population as people who typically buy or receive gift cards. — CivicScience
- [ST08] Federal Trade Commission: Consumer Sentinel Network Data Book 2024, printed page 11. Original payment-method table and reported-loss inclusion notes. — Federal Trade Commission
In this article
Oliver Reed
Oliver Reed covers industry acquisitions, investment and market research for Gift Card News.